GST physical verification checks the declared business premises under the applicable registration route. It is not itself a rejection, and a clarification notice is not a final refusal. Before reacting to “GST registration rejected”, download the actual communication and identify whether it is REG-03, REG-05 or a portal message. Circular 257, paras 5.4–5.6
The useful next step depends on that distinction. A missing lease page can be corrected in a pending application; a rejection order needs a review of the recorded reasons and available remedies. Do not buy a new address until you understand what failed.
GST physical verification, clarification or rejection?#
| What you received | What it usually means | First action |
|---|---|---|
| Direction for authentication/document verification | A facilitation-centre identity/document step applies. | Follow the official intimation and complete the required verification. |
| Selection for premises verification | The physical place is to be checked under the relevant route. | Confirm genuine access, correct directions and occupation evidence. |
| REG-03 | The application needs a clarification or specified correction. | Read each point and prepare a REG-04 reply within the applicable period. |
| REG-05 rejecting registration | A reasoned rejection decision has been issued. | Save the order and assess correction/reapplication or appeal. |
| Upload/login/status failure | It may be a technical issue rather than a legal refusal. | Preserve the error and raise a GSTN ticket where appropriate. |
The first four distinctions follow Circular 257, paras 5.2–5.6. For portal problems, use the GSTN self-service system. Check your ARN and official account rather than relying on a screenshot forwarded without the underlying order.
If an existing GSTIN was cancelled, that is a different proceeding from rejection of a fresh application. Do not submit a new-registration reply as though it were a revocation application. Have the professional identify the exact order and statutory route before calculating deadlines.
Address-proof reasons and proportionate fixes#
The following are diagnostic examples grounded in the circular, not a claim about how often officers reject applications.
| Reason or query | What it means | Fix to assess | Reference |
|---|---|---|---|
| Address differs between REG-01 and proof | The declared place is not clearly established. | Reconcile building, floor/unit, locality and PIN against valid documents. | Paras 3.7.2 and 5.4 |
| Scan incomplete or unreadable | The document cannot be assessed. | Upload complete legible pages, including signatures and relevant registration particulars. | Paras 3.8.7 and 5.4 |
| Co-working membership omits allotted desk/period | The specific occupation is undocumented. | Obtain a correctly executed membership with the required particulars. | Para 3.8.5 |
| Leased co-working centre omits owner–provider registered lease | A required supporting link is missing. | Ask the provider for the valid registered lease and review the legal names. | Para 3.8.5 |
| Parent/director-owned property declared as applicant-owned | The possession category is inaccurate. | Review consent/rental classification and supporting evidence. | Para 3.8.2.1 and FAQ Q.22 |
| Consent is unsigned or owner proof missing | Permission and/or supporting property evidence is incomplete. | Obtain final signed Annexure VI and qualifying consenter-name document. | Para 3.8.4 |
| Direct tenancy agreement should have been registered | Applicable law/document route has not been satisfied. | Have the parties regularise the instrument and evidence. | Para 3.8.3(a)(i) |
| Applicant or landlord photograph demanded as premises proof | This is not the specified application evidence. | Explain the applicable document route and cite FAQ Q.35. | FAQ Q.35 |
| Objection solely because signatory lives in another state | Potential presumptive query. | Explain the true circumstances and refer to the circular’s restriction. | Para 5.4.1 |
Use the GST document checklist to identify the missing item. The GST NOC tool is for genuine consent-basis premises, while the rent agreement guide explains tenancy and no-agreement evidence.
Correct facts at their source. If a membership has the wrong applicant name, ask the provider to correct and execute it. Do not alter a signed PDF yourself or upload a different business’s document as a convenient substitute.
What officers may ask under Circular 257#
Paragraph 5.4 identifies clarification grounds including incomplete or illegible documents, premises-address mismatches and incomplete/vague addresses. The circular calls for formal electronic communication in REG-03 when information needs correction. Circular 257, paras 5.4 and 6
Paragraph 5.4.1 cautions against irrelevant presumptive queries: examples include the signatory’s residence being elsewhere, demands for an Udyam certificate and unsupported objections that the described business cannot operate from those premises. Paragraph 6 also rejects subjective assessments of utility-bill amounts or residential suitability. Circular 257, paras 5.4.1 and 6
These protections do not mean every shared-address application must be approved regardless of evidence. An allotted space, valid documents and accurate application still matter. Respond with the actual facts and the relevant paragraph, rather than asserting that all questions are prohibited.
If a query mixes a genuine omission with an unwarranted demand, answer the valid point fully and explain the disputed point separately. This makes the response easier to assess and avoids letting an argument about one request obscure the missing evidence.
How to prepare a REG-04 reply#
The circular gives seven working days from receipt of REG-03 for the reply. The officer’s decision period after receiving the reply is seven working days. Diarise the notice date and applicable deadline immediately; do not use the date your adviser happens to open the email as an assumed legal starting point. Circular 257, para 5.5
A practical response file has four parts:
- Identification: applicant name, ARN, notice reference and date.
- Point-by-point answer: reproduce each issue briefly and explain the relevant facts.
- Evidence map: identify the document and page supporting each answer.
- Requested action: ask for consideration of the corrected evidence under the applicable provisions.
This is a drafting approach, not an official universal reply template. Use the live REG-04 fields and attachments. Do not send only an informal message to a workspace salesperson and assume the statutory reply has been filed.
For an address mismatch, identify which description was wrong and what has been corrected. For a missing head lease, provide the actual registered document rather than another bill. For a disputed presumptive question, cite the exact paragraph and explain the real business model truthfully.
Before submission, open every attachment again. Keep the filed reply and acknowledgement with the original notice. An internal draft or an email saying “we will reply” is not evidence that the portal received the response.
What happens during GST physical verification?#
A premises visit under Rule 25 differs from Aadhaar/biometric verification at a facilitation centre. An applicant can successfully authenticate Aadhaar and still be selected for premises verification through the risk-based process. Circular 257, paras 5.1–5.2 and 5.6
Paragraph 5.6 directs the officer to record whether the principal place exists. If it cannot be found, the report should describe efforts to locate it. The officer uploads REG-30, with GPS-enabled site photographs and other relevant documents, at least five days before expiry of the thirty-day period. Circular 257, para 5.6
REG-30 is the officer’s report; applicants do not prepare a fabricated version for their REG-01 upload. Equally, FAQ Q.35’s rejection of applicant/landlord photographs as premises proof does not prevent the officer from taking the required site photographs. Circular 257, para 5.6 and FAQ Q.35
Prepare the premises honestly#
Confirm the correct entrance, floor and allocated unit, and how the responsible person can be contacted. Keep the executed occupation documents available. If the application concerns a shared desk, explain that arrangement consistently with the membership.
Do not stage stock, equipment or staff that do not exist. If goods are genuinely stored elsewhere, review the relevant additional-place or separate-state registration position with your CA. Paragraph 3.9 treats additional places within the registration state and applies the same premises evidence principles. Circular 257, para 3.9
If the visit is assigned to the wrong jurisdiction, paragraph 5.6(d) addresses reassignment through the portal. Preserve the correct address and PIN evidence and raise the mapping issue through the proper channel rather than changing the location to fit an incorrect assignment. Circular 257, para 5.6(d)
Co-working addresses and the missing lease chain#
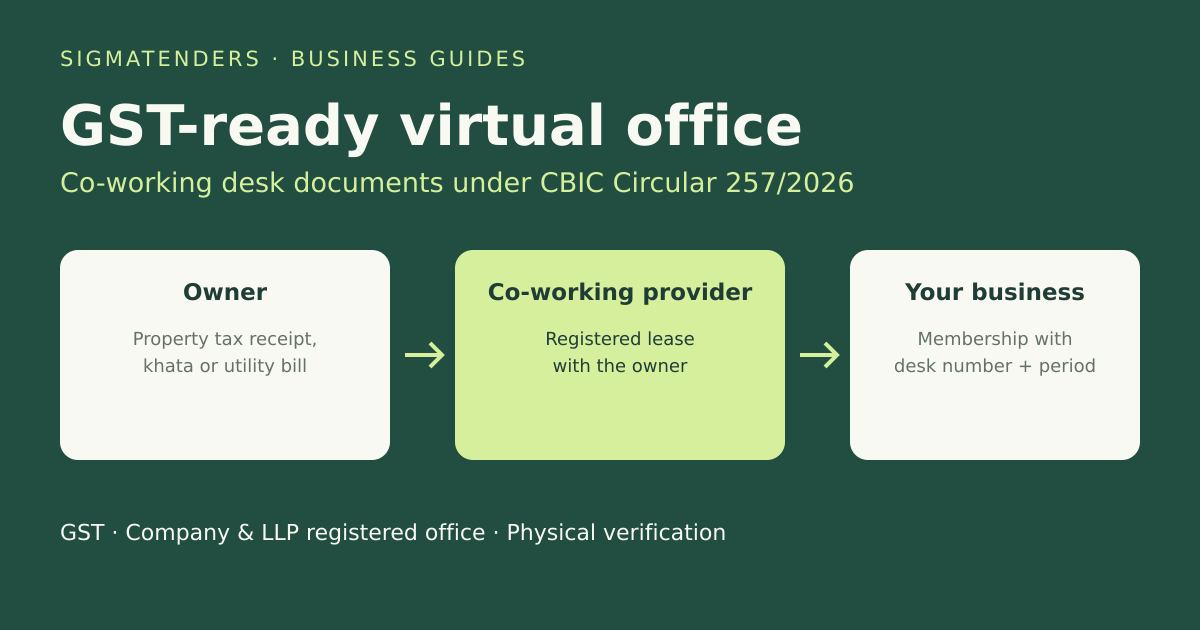
The circular does not mention “virtual office”. It specifically describes co-working premises with a membership identifying the allocated desk/cabin/suite, agreement period and provider ownership/lease status. An address-only plan without those rights and documents is weaker. Circular 257, para 3.8.5
Where the provider rents, the prescribed supporting document is the valid registered lease between owner and provider. If that cannot be produced, another generic NOC does not cure the missing chain. Review the GST-ready virtual office guide before purchasing a replacement.
Ask who is contractually obliged to resolve a document deficiency and whether the proposed replacement is genuinely different. Moving to another desk under an equally incomplete head-lease arrangement may reproduce the same problem.
Timelines and deemed approval#
Ordinary successful Aadhaar-authenticated applications use the seven-working-day route described in paragraph 5.1. Non-authentication, failed authentication and the relevant physical-verification cases use the thirty-day route. Facilitation-centre completion affects when an application is deemed complete. Circular 257, paras 5.1–5.2
Paragraph 5.7 provides deemed approval if the proper officer takes no action within the applicable Rule 9 period. A timely REG-03 changes the processing stage and brings the reply/decision periods into consideration. Calculate the full sequence before claiming a deadline has passed. Circular 257, paras 5.4.2–5.7
Keep a simple chronology: submission, authentication completion, ARN, notice receipt, reply submission and any visit. This helps distinguish a departmental delay from an incomplete authentication step or an unanswered notice. A seller’s “approval in days” promise is not evidence of the statutory timeline in your case.
Reapplying or challenging a rejection#
FAQ Q.18 says an applicant may make a fresh application after correcting deficiencies in the rejection order. Reapplication is useful only when the defect is actually fixed. Retain the earlier application and disclose relevant prior registration facts accurately. Circular 257, FAQ Q.18 and para 4
An appeal may also require consideration. General official appeal guidance describes a three-month period from communication of the decision/order, with a possible further month of condonation for sufficient cause. The available route, documents and limitation calculation must be assessed against your actual rejection order. GST portal appeal FAQs
A helpdesk ticket or grievance is not a substitute for an appeal and should not be assumed to stop a legal deadline. Obtain prompt professional review if you disagree with the order, especially where there are repeated rejections or a disputed legal ground.
Grievances and requests for money#
For technical failures, use the GSTN self-service portal with the ARN, error details, date and relevant screenshots. Describe the technical problem precisely and retain the ticket reference.
For undue delay or unwarranted registration queries, paragraph 8 points to the jurisdictional Chief Commissioner of Central Tax or Commissioner of State Tax. Use the applicable department’s current published grievance route. Circular 257, para 8 CPGRAMS is an additional official public-grievance channel; it does not replace filing obligations or judicial remedies.
Refuse requests for unofficial payment. Record the facts safely and report them through the relevant official grievance/vigilance channel or the state’s official anti-corruption bureau, as appropriate. CBIC vigilance guidance Do not pay a private intermediary to “settle” an officer’s demand. Use verified official contact details rather than a number supplied by the person requesting money.
SigmaTenders can assist with document review, CA-supported applications and physical-verification preparation. Partner-space desk documents and mail handling are price on request, and available through partner spaces; we confirm availability in your city within 48 hours. Ask us about correcting your GST address documents. For a fresh filing, start with the registration hub.
GST physical verification and rejection FAQs#
Does physical verification mean my GST registration is rejected?
No. It is a verification route. A rejection is communicated by the relevant order; distinguish that from selection for a visit or a REG-03 clarification. Circular 257, paras 5.4–5.6
Can I reply after receiving REG-03 instead of reapplying?
REG-03 is a pending-application clarification. Reply in REG-04 within seven working days of receipt under the circular, with the evidence addressing each point. Para 5.5
What if the officer asks for a landlord selfie?
FAQ Q.35 says landlord/applicant photos are not required or accepted as premises proof. Explain the prescribed documents; officer GPS site photos remain a separate process. FAQ Q.35 and para 5.6
Can I submit another application after REG-05?
FAQ Q.18 permits a fresh application after correcting the stated deficiencies. Ask a professional whether an appeal also needs consideration and preserve the order dates. Circular 257
Will a grievance guarantee approval?
No. A grievance raises an issue for the relevant authority. Approval still depends on the legal requirements and evidence, and the grievance does not replace a notice reply or appeal.