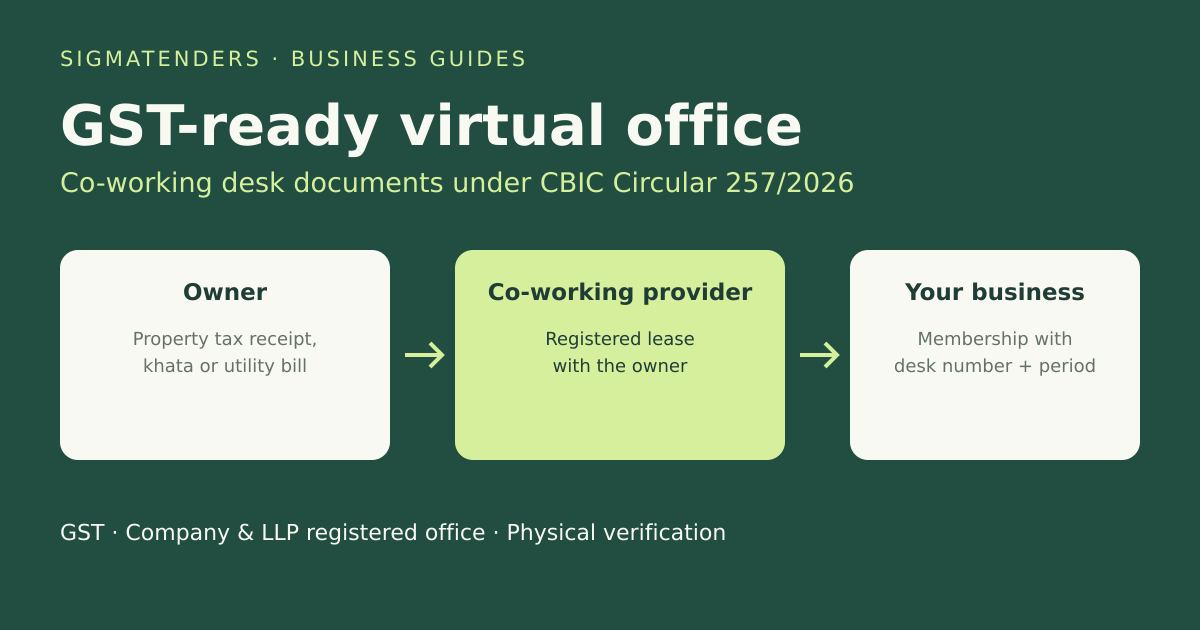
A virtual office for GST registration should give you an identifiable co-working desk and the documents connecting it to the property owner. Paragraph 3.8.5 of CBIC Circular No. 257/03/2026-GST requires a membership agreement stating its period and allotted suite, cabin or desk number, backed by the provider’s ownership proof or registered owner–provider lease. A mailing address alone does not establish that structure. Circular 257, 26 October 2026, para 3.8.5
SigmaTenders helps Indian founders obtain a GST-ready virtual desk through verified partner co-working spaces, with CA-assisted application support. Price on request. Start by checking the paperwork before choosing an address.
Can you use a virtual office for GST registration?#
Co-working premises are expressly covered; “virtual office” is not a term used in Circular 257. Its document route concerns an allocated physical space. Annexure III and FAQ Q.26 reinforce the membership-plus-property-evidence requirement. Therefore, assess a virtual office address for GST registration by the rights and documents supplied, rather than the plan’s marketing name. Circular 257, para 3.8.5, Annexure III and FAQ Q.26
The principal place of business, or PPoB, is the primary business location within the state where you apply. It needs a precise, supportable address. You do not establish it simply by receiving a courier there. Circular 257, paras 3.7.1–3.7.2
| What the plan supplies | What to check before buying |
|---|---|
| Address-only mail service | Does it actually allocate physical space and supply the co-working documents? Without those, it does not demonstrate the para 3.8.5 route. |
| Co-working desk membership | Can you identify the desk, use it under the agreement and obtain the provider’s property evidence? |
| Desk supplied through an intermediary | Which entity is your membership provider, and can it produce its ownership proof or registered lease with the owner? |
These buying checks apply the para 3.8.5 document requirements. See our broader virtual office guide for choosing the service; use the registered-office address guide when your enquiry also concerns MCA filings.
Exact co-working documents under Circular 257#
Ask to inspect a sample pack before paying. The key connection is property owner → co-working provider → applicant. An invoice for address services does not explain that connection.
| Document | Required contents or supporting evidence |
|---|---|
| Applicant’s membership agreement | Agreement period; specific suite, cabin or desk number; whether the provider owns or rents/leases the premises. FAQ Q.26 also specifies the full address and allocated space. |
| Provider owns the premises | Membership agreement plus one qualifying property document in the provider’s name for that address. |
| Provider rents or leases the premises | Membership agreement plus the valid registered rent/lease agreement between the owner and co-working provider. |
| Qualifying ownership evidence | Latest property-tax receipt, municipal khata, property-identification document, latest electricity bill or latest water bill, with the relevant name and complete address. |
The table follows Circular 257, paras 3.8.2.2 and 3.8.5; FAQ Q.26. These are alternatives according to ownership status, not a requirement to collect every listed bill.
For a leased co-working centre, the provider’s electricity bill alone does not replace the registered owner–provider agreement specified in para 3.8.5. Ask who owns the premises, who holds that lease, and who will sign your membership. If those names do not connect, have the provider resolve the gap before submission. Circular 257, para 3.8.5
Rent and consent are different document routes#
For a direct tenancy, para 3.8.3 distinguishes a registered agreement from an agreement that does not require registration. The latter generally needs the lessor’s supporting premises document. Do not automatically apply that exception to a co-working provider’s head lease: para 3.8.5 expressly calls for its registered agreement. Circular 257, paras 3.8.3 and 3.8.5 Our rent agreement for GST guide explains the separate tenancy route.
For premises made available on consent, para 3.8.4 and Annexure VI specify the signed consent and supporting property evidence. A parent’s or director’s ownership does not make the applicant entity the owner. FAQ Q.37’s co-owner exception concerns an applicant who itself jointly owns the property; it is not a general waiver for every consent arrangement. Circular 257, paras 3.8.2.1 and 3.8.4; FAQ Q.37
Use the GST NOC / consent letter generator to prepare a draft for review where appropriate. It does not replace the co-working membership and provider evidence.
Check your pack before REG-01
- Match the applicant’s name across the membership and application.
- Check the allotted desk number, address and agreement dates.
- Identify the provider’s ownership document or registered owner–provider lease.
- Open every scan and check signatures, complete pages and legibility.
- Keep the final signed versions ready for the CA’s review.
This preparation checklist supports paras 3.7.2, 3.8.5 and 3.8.7. The GST document checklist covers the wider application beyond premises proof.
REG-01 walkthrough: principal place of business#
In Part B, work through the Principal Place of Business section against the signed documents. Circular 257, para 3.2.1 Keep a final address sheet beside the form; do not copy an abbreviated sales address.
1. Enter a precise address and confirm the map marker#
Include the building, floor/unit and allotted space as applicable, road, locality, city, district and correct PIN code. Paragraph 3.7.2 asks for premises-level precision and an address matching the uploaded proof. A locality or road name alone is insufficient. Circular 257, para 3.7.2
Use the map to locate the premises, move the marker if necessary, and confirm it. Review any auto-populated address before saving. Latitude and longitude should identify the actual premises; the circular says to provide them as far as possible. A correct map pin does not cure an incorrect unit number in the documents. GST portal manual, PPoB section; Circular 257, para 3.7.2
2. Check state and central jurisdiction#
Confirm both jurisdictions using the address and PIN code. Paragraph 3.7.3 explains that incorrect selection can delay processing or require reassignment for verification. Also provide working business contact details. Circular 257, para 3.7.3
3. Match nature of premises to your actual arrangement#
The portal manual calls this Nature of Possession of Premises. Labels may change: where a dedicated co-working option is displayed, use it for that arrangement. Otherwise, have your CA match the available option to the agreement rather than selecting whichever needs fewer uploads. GST portal manual; Circular 257, paras 3.8.2.1–3.8.5 and Annexure III
| Selection to assess | Arrangement to substantiate |
|---|---|
| Shared | Shared occupation, including a co-working desk where this is the applicable available label; retain the para 3.8.5 pack. |
| Rented / leased | A tenancy or lease granted to the applicant; follow para 3.8.3 for that arrangement. |
| Consent | Owner-permitted use on consent; follow para 3.8.4 and Annexure VI. |
| Own | Ownership by the applicant itself, not merely its founder or director. |
The classification follows Circular 257, paras 3.8.2–3.8.5. Your possession category and the nature of business activities are separate fields: describe the activity actually conducted there. Circular 257, para 3.7.3
4. Upload readable evidence and review the saved application#
Check the limit displayed beside each upload. The official manual currently states 1 MB for PPoB proof, while its 2 MB allowance concerns e-KYC documents. A file exceeding 2 MB is therefore not the only possible problem: a smaller premises file can still exceed its field limit. Compress without losing readable names, addresses, signatures or registration details. GST portal manual, document-upload sections
Reopen the saved details and files before submission. Ask the CA to resolve inconsistent descriptions instead of removing pages that establish the lease chain.
Physical verification: what happens at the desk?#
Aadhaar authentication does not prevent selection for physical verification under the risk-based process. Rule 25 is the premises-verification mechanism referenced by the circular. Paragraph 5.6 directs the officer to report specifically whether the declared PPoB exists, record efforts to locate it if it does not, and upload GPS-enabled site photographs and relevant documents. Circular 257, paras 5.1 and 5.6
The officer’s report goes into FORM GST REG-30, at least five days before the 30-day processing period expires. It is an officer’s filing, not an extra report the applicant uploads with REG-01. Circular 257, para 5.6
Recommended preparation: confirm how an officer will reach the correct building, floor and allotted desk. Keep the membership and property evidence accessible. Ask the provider how it identifies your allotment and handles official visits and mail. Explain your actual activity accurately; do not stage stock, staff or equipment that your business does not have.
FAQ Q.35 says photos of the applicant or landlord at the premises are neither required nor accepted as PPoB proof. That differs from the officer’s GPS-enabled photographs during verification, and from biometric-centre photographs under para 5.2. A selfie does not replace the premises documents. Circular 257, FAQ Q.35 and paras 5.2, 5.6
Aadhaar authentication and registration timelines#
The following are the ordinary processing routes described in the circular, not delivery promises from SigmaTenders.
| Route or event | Processing position |
|---|---|
| Successful Aadhaar authentication, ordinary route | Seven working days from submission, subject to the applicable verification route. |
| No Aadhaar authentication, failed authentication, or selection/authorised referral for physical verification | Thirty days from submission, with premises verification. |
| REG-03 clarification notice | Applicant replies in REG-04 within seven working days of receipt; officer decides within seven working days of receiving the reply. |
| No officer action within the applicable Rule 9 period | Deemed approval under para 5.7. A timely notice changes the relevant processing stage. |
Sources: Circular 257, paras 5.1, 5.4.2, 5.5 and 5.7.
Where biometric authentication or original-document verification at a facilitation centre applies, complete that step promptly: para 5.2 links application completeness to successful verification. Do not count only from the day you began a draft. Special routes under Rules 14A and 9A have separate eligibility and processing provisions; ask your CA whether either applies. Circular 257, paras 5.2–5.3
Common document problems and how to fix them#
Treat these as checks for an application or notice, not a claim about rejection rates or a substitute for reading the officer’s actual grounds.
| Problem | Practical fix | Source |
|---|---|---|
| Service agreement describes mail handling but omits allotted space or period | Obtain a membership agreement containing the required particulars. Renaming the PDF is insufficient. | Para 3.8.5 |
| Provider leases the property but omits its owner–provider lease | Obtain the valid registered agreement alongside your membership. | Para 3.8.5 |
| Address differs between REG-01 and evidence | Correct the erroneous form or document; reconcile the building, unit and PIN before responding. | Paras 3.7.2 and 5.4 |
| Upload exceeds 2 MB, or the smaller field-specific limit | Read the actual field limit; compress legibly and check the uploaded copy. | GST portal manual |
| Objection assumes your activity cannot operate at these premises | Explain the real activity and evidence; cite the restriction on irrelevant presumptive queries. | Para 5.4.1 |
A clarification notice is not a rejection order. Use REG-04 to answer each REG-03 point within the deadline; the circular describes a reasoned rejection in REG-05 where the reply is unsatisfactory. For delays or unwarranted queries, para 8 provides escalation to the jurisdictional Chief Commissioner of Central Tax or Commissioner of State Tax. Circular 257, paras 5.5 and 8 See GST registration rejected: next steps for handling an actual order.
Who should choose different premises or get specialist advice?#
A desk may suit a service business whose actual arrangements support that location. Freelancers can first compare home and co-working options in our GST registration for freelancers guide.
Our suitability recommendation: exporters expecting refunds and traders passing substantial input tax credit should get a CA’s review before buying a virtual address for GST. Their operational evidence deserves particular attention. This is not a legal ban or a verified rule that every such applicant faces extra scrutiny. The circular recognises risk-based verification while prohibiting presumptive objections about business activities. Circular 257, paras 5.1 and 5.4.1
Do not choose a desk-only plan if you need storage, manufacturing facilities or regular customer access that it cannot provide. If stock is held away from your PPoB, declare the actual warehouse or storage premises appropriately as an APOB within that state. The definition of place of business includes goods-storage locations; a virtual desk does not document the stock location. CGST Act, section 2(85); Circular 257, para 3.9
APOB and premises in other states#
An APOB belongs to the same state’s registration. Do not add another state’s warehouse to your existing GSTIN as though it were a local APOB. Registration liability in that state needs a separate assessment; selling to customers there alone does not establish that you operate from there. Circular 257, para 3.9; CBIC sectoral FAQs, registration Q.22
Read our GST registration for e-commerce sellers guide before choosing a multi-state address arrangement.
What SigmaTenders provides#
Our GST-ready address service is structured as a co-working membership with an allotted desk number through verified partner spaces. We help with:
- Document pack: membership with desk number and period, plus the provider’s ownership proof or registered lease.
- CA-assisted filing: support preparing and submitting the GST application; MCA application support where required.
- Verification preparation: reviewing the premises documents and preparing for the relevant verification process.
- Mail handling: handling business mail through the partner arrangement.
Price on request. The service is available through partner spaces; we confirm availability in your city within 48 hours. That availability response is separate from the GST department’s processing time.
For location-specific guidance, see Delhi GST addresses, Bangalore GST addresses or Mumbai GST addresses. For broader application help, see GST registration.
Ask us about a GST-ready address in your city, with your business activity, state and whether you hold stock or expect refund claims. Those details help us assess the appropriate arrangement before quoting.
Frequently asked questions#
Is a virtual address for GST registration enough by itself?
For the co-working route, prepare the membership naming your allocated space and agreement period, together with ownership evidence or the registered owner–provider lease. An address-only receipt does not supply those documents. Circular 257, para 3.8.5 and FAQ Q.26
Can I get GST registration without an office of my own?
You need not own premises: the circular describes rented, consent and co-working routes. Choose the route matching your actual occupation and evidence. Circular 257, paras 3.8.3–3.8.5
Does virtual GST registration avoid physical verification?
No. A co-working membership does not remove the risk-based verification route or applicable biometric requirements. Prepare for both identity verification and a premises visit where selected. Circular 257, paras 5.1–5.2 and 5.6
Should I choose shared, rented or consent for a co-working space?
Match the live form’s option to your agreement, using a dedicated co-working option if available. Shared occupation, a direct tenancy and owner consent require different evidence; do not claim ownership merely because your director owns the property. Circular 257, paras 3.8.2.1–3.8.5
Do I need a landlord photograph or every co-owner's NOC?
FAQ Q.35 rejects applicant/landlord photos as premises proof. FAQ Q.37 removes the other-co-owner NOC requirement where the applicant jointly owns the property; consent arrangements have their own requirements under para 3.8.4. Circular 257, FAQs Q.35, Q.37 and para 3.8.4
What does a GST-ready virtual desk cost?
SigmaTenders pricing is price on request. We confirm partner-space availability in your city within 48 hours. Ask for the scope covering the document pack, CA-assisted application support, verification preparation and mail handling before choosing a plan.