GST e commerce registration starts with your selling model and stock locations. A qualifying small seller can use a conditional exemption for intra-state goods sales through a marketplace. A seller expanding into fulfilment centres needs to assess registration in each dispatch state. These are different decisions; marketplace sign-up alone does not settle either. Notification 34/2023–Central Tax · Amazon’s state and fulfilment-centre guidance
Before choosing an address package, list where your goods will actually sit. Then work through exemption eligibility, the relevant state registration and the documents for each location.
GST e commerce registration: who must register?#
Section 24(ix) generally requires registration for suppliers selling through an electronic commerce operator required to collect tax at source under section 52, excluding section 9(5) supplies. But notified exemptions matter: “every online seller needs GST regardless of turnover” is incomplete. The circular’s FAQ Q.3 expressly recognises notified exemptions. CGST Act, section 24 · Circular 257, FAQ Q.3
The conditional exemption for small goods sellers#
Notification 34/2023–Central Tax, effective 1 October 2023, exempts eligible marketplace goods suppliers from registration. Aggregate turnover in both the preceding and current financial years must remain within the applicable state or Union territory registration threshold. The conditions include:
- No inter-state supply of goods.
- Goods sales through e-commerce operators in only one state or Union territory.
- A PAN, with PAN, business address and chosen state declared and validated on the GST portal.
- A portal-issued enrolment number before marketplace supplies begin; only one enrolment number per state or Union territory.
The enrolment ceases to be valid when subsequent GST registration takes effect. This is an enrolment route, not a GSTIN. Notification 34/2023, conditions (i)–(viii)
Do not treat a marketplace’s sales total as your entire turnover assessment. The circular describes annual aggregate turnover on a PAN basis and advises checking the applicable state threshold. Ask your CA to review your other sales channels, product categories and any independent compulsory-registration trigger. Circular 257, FAQs Q.1–Q.3
The operator has duties too: under Notification 37/2023 it must validate the enrolment route, prevent inter-state supplies by these sellers, report their supplies in GSTR-8 and refrain from collecting section 52 TCS on those supplies. Platform support and your legal eligibility therefore need separate checks. Notification 37/2023–Central Tax
Exempt goods, services and composition are separate cases#
Persons dealing exclusively in wholly exempt or non-taxable supplies have a separate section 23 position. For marketplace services outside section 9(5), Notification 65/2017 provides turnover-based relief, amended by Notification 06/2019. A goods seller should not borrow a services exemption. CGST Act, section 23 · Notification 65/2017 · 2019 amendment
Composition taxpayers can make qualifying intra-state goods supplies through operators, subject to the applicable conditions. Composition is a registered taxpayer scheme; it is different from unregistered-seller enrolment and does not solve multi-state fulfilment needs. Government’s explanation of the changes
What Amazon, Flipkart and Meesho say#
Use these official sources when planning GST registration for an e commerce business. A platform’s onboarding requirements do not replace the exemption notifications.
| Marketplace | Official guidance checked | Practical next step |
|---|---|---|
| Amazon | Its seller FAQ asks for GST details for taxable goods and recognises exempt-category cases. Its FBA FAQ says to register the fulfilment centre as an additional place of business. | Confirm the category and proposed FC before arranging documents. |
| Flipkart | The sell-online page includes GST enrolment guidance. Its official location-onboarding documentation requires dispatch-location information, including the corresponding registered address and GSTIN details. | Confirm the current FBF warehouse document pack and account workflow in Seller Hub. |
| Meesho | Its official prospectus says sellers can onboard without GST registration in compliance with applicable regulations. | Check the current supplier-panel route alongside Notification 34/2023 eligibility. |
We could not verify a publicly accessible Flipkart APOB document checklist. Do not assume Amazon’s document names or upload sequence apply to FBF. Get the exact facility address and current instructions from Flipkart before filing. For account setup, use our separate Flipkart and Amazon seller registration guide.
PPOB, APOB and VPOB: map the addresses first#
PPOB means principal place of business. APOB means additional place of business. A warehouse or other place where goods are stored falls within the statutory definition of a place of business. The circular says additional locations belong to the state of registration. CGST Act, sections 2(85) and 2(89) · Circular 257, para 3.9
VPOB, sometimes written VPPoB, is marketplace terminology for a virtual principal place of business arrangement. Amazon describes a third-party premises arrangement supporting registration in another state. It is not a substitute for identifying the actual PPOB on the application. Amazon’s VPPoB explanation
For planning, keep one row for each proposed facility: state, marketplace, FC identifier, full address, intended GSTIN and document status. Keep buyer destinations in a separate column so they are not confused with dispatch locations.
FC in the same state: add an APOB#
For an ordinarily registered seller with a valid GSTIN in that state, an additional marketplace FC is generally an APOB amendment, rather than a new-state registration. File REG-14 with the premises evidence. Circular para 3.9 applies the relevant premises-document requirements to amendments too. Circular 257, para 3.9 · GST Council’s APOB amendment FAQ, question 3
FC in another state: assess a new state GSTIN#
In Amazon’s ordinary FBA arrangement, selling or shipping from multiple states requires the corresponding state GSTINs. The conventional structure is a PPOB in the new state plus the FC as APOB. A properly documented co-working desk can support that PPOB application. Amazon’s existing help says its FC cannot be the PPOB in this conventional arrangement; read that alongside the newer Rule 14B option below. Amazon’s FBA registration guidance · Circular 257, para 3.8.5
For example, a Maharashtra-registered seller considering a Karnataka FC should assess a Karnataka registration before moving stock. Merely serving Karnataka buyers from Maharashtra is a different fact pattern. The important distinction is where supplies are made from, rather than every state in which a customer lives. CGST Act, sections 22 and 25
New Rule 14B: check the warehouse option before buying a desk#
From 1 November 2026, Rule 14B permits qualifying sellers with a home-state registration and physical presence there to seek registration in another state where they lack physical presence, declaring an e-commerce operator’s warehouse as PPOB. Operator consent is essential. The rule includes a monthly ₹2.5 lakh output-tax-liability ceiling on the specified supplies to registered persons, excluding same-PAN recipients; this is not a turnover ceiling. Notification 05/2026, rule 14B(1)–(5)
This remains a state registration route, not a single nationwide GSTIN or an exemption from registration. Ask your CA and marketplace whether you meet the conditions and can obtain the required consent before choosing between this route and a separate co-working PPOB. Do not assume an older marketplace help page describes the new scheme’s implementation. Rule 14B scheme FAQs
Co-working PPOB: the desk and document chain matter#
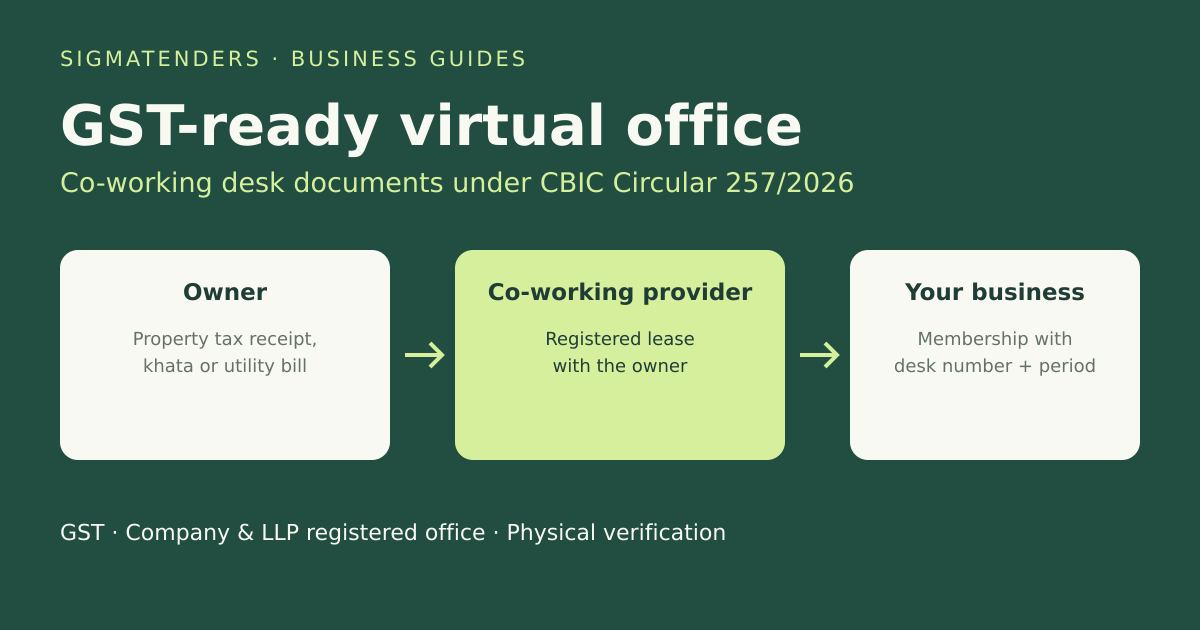
CBIC Circular No. 257/03/2026-GST does not mention “virtual office”. Para 3.8.5 expressly addresses co-working spaces. The documented structure is a membership with an allotted suite, cabin or desk and evidence of the provider’s title or registered lease. An address-only plan without an allotted desk and the correct document chain is weaker evidence against that checklist. Circular 257, para 3.8.5 and FAQ Q.26
| Evidence | What to check |
|---|---|
| Membership agreement | Agreement period, specific allotted suite/cabin/desk number and whether the provider owns or leases the premises. |
| Provider owns the premises | One of the prescribed ownership/address documents in the provider’s name, such as the latest property-tax receipt, municipal khata, property-identification document, electricity bill or water bill. |
| Provider leases the premises | Valid registered rent/lease agreement between the property owner and co-working provider, in addition to your membership agreement. |
| Application address | Complete, specific address matching the uploaded premises document; check the map marker and PIN code. |
These requirements follow paras 3.7.2 and 3.8.5. A desk membership does not supply the FC’s separate premises evidence. Keep the two document packs clearly labelled for the CA.
Ordinary rented premises follow para 3.8.3. Family/director-owned premises provided on consent follow para 3.8.4 and Annexure VI. Choose the actual arrangement rather than labelling every permission letter as a co-working membership. Circular 257, premises-document categories
Our virtual office for GST registration guide explains this evidence chain in more detail. Compare the agreement itself before comparing address-service descriptions.
Adding or removing an FC through REG-14#
The amendment process changed in November 2026. The substituted Rule 19 requires REG-14 within fifteen days of the change. Ordinary APOB changes are processed automatically under the revised framework; older instructions describing every APOB addition as an officer-approved core amendment need updating. Rule 14B warehouse-address amendments have their own operator-consent requirement. Notification 05/2026, substituted rule 19 and rule 14B(16)
Use this practical filing sequence with your CA:
- Confirm the state and GSTIN. Match the FC to the registration it will sit under.
- Collect premises evidence. Use the current marketplace documents and the applicable REG-01 premises checklist; para 3.9 extends that checklist to amendments. Circular 257, para 3.9
- Submit REG-14 on the GST portal. Check the applicable amendment route against the revised process. Official APOB amendment FAQ
- Check the resulting certificate. Compare the address against the FC documents before updating marketplace records. Certificates can be downloaded through the portal’s View/Download Certificates facility. GST portal manual
- Review locations when leaving a facility. Amazon’s GST FAQ instructs sellers to remove discontinued or closed FC addresses through REG-14. Amazon GST compliance FAQ
Keep the application acknowledgement, submitted documents and resulting certificate together. Automatic processing does not make inaccurate premises information acceptable. Circular 257, para 3.9
Multi-state sellers: prepare for scrutiny and keep books accessible#
Treat multi-state trading as a high-scrutiny planning scenario: more stock locations and registrations create more records to reconcile. This is our practical risk assessment, not a published government risk ranking. The circular explains the concern about fake registrations and unsupported input tax credit while requiring fair handling of genuine applications. Circular 257, paras 1.1–1.4
For ordinary registrations, section 35 requires accounts at the PPOB, with location-related records at the relevant places and electronic maintenance permitted as prescribed. Under Rule 14B, the special arrangement places the registration-wise books and records at the home-state PPOB, with production on demand. Agree who can retrieve records before signing an address membership. CGST Act, section 35 · Rule 14B obligations FAQ, question 10
Recommended state-wise readiness file
- Current registration certificate and premises agreements.
- FC address evidence and amendment acknowledgements.
- Stock, dispatch, return and transfer records organised by facility.
- Sales, purchase and tax records organised by GSTIN.
- A named person who can retrieve electronic records.
- Mail-handling contacts, membership renewal dates and portal-notice ownership.
Para 5.4.1 bars irrelevant presumptive queries, including objections based merely on the signatory living in another state or assumptions about activities at the premises. Physical verification remains possible: para 5.6 requires REG-30 reporting with GPS-enabled site photographs. FAQ Q.35 concerns applicant/landlord photographs as premises proof; it does not abolish site verification. Circular 257, paras 5.4.1 and 5.6; FAQ Q.35
Arrange the address after choosing the registration route#
SigmaTenders helps Indian founders with registrations and compliance. Our GST-ready virtual desk / registered-office address is provided through verified partner co-working spaces, structured as a membership with an allotted desk number under para 3.8.5. We help with the address and document pack, GST/MCA application support with a CA, preparation for physical verification and mail handling. Co-working document basis
The service is available through partner spaces; we confirm availability in your city within 48 hours. Pricing is price on request. Review our virtual office service, GST document checklist and GST registration support. Ask us about a GST-ready address for your proposed fulfilment state, with the marketplace and intended stock location.
This is general information, not legal or tax advice. Have a CA/CS assess your exemption, registration route and actual documents; an address membership does not guarantee registration approval.
Frequently asked questions#
Is GST registration compulsory for e commerce sellers below the turnover threshold?
Not always. Eligible goods sellers can use the conditional intra-state enrolment exemption. Check every condition before relying on it. Notification 34/2023
What does an e commerce operator mean in GST?
It is the person owning, operating or managing the electronic platform. Selling goods through that platform does not by itself make you the operator. CGST Act, section 2(45)
Does Amazon seller GST registration cover every fulfilment state?
Amazon’s ordinary FBA guidance requires the relevant state GSTIN when shipping from multiple states. Confirm the FC state before arranging registration. Amazon FBA help
Can I add a fulfilment centre as an additional place of business?
For an existing registration in that state, use REG-14 with the applicable premises evidence. A different-state FC needs a state-registration assessment. Circular 257, para 3.9
Must I buy a virtual office for GST registration for ecommerce?
Assess Rule 14B first: qualifying sellers may use an operator’s warehouse with consent. For a co-working PPOB, obtain the allotted-desk membership and provider documents. Rule 14B FAQs · Circular 257, para 3.8.5
Does selling on Meesho without GST allow inter-state orders?
The unregistered-seller procedure requires the operator to prevent inter-state supplies. Platform enrolment does not override that restriction. Notification 37/2023, clause (ii)