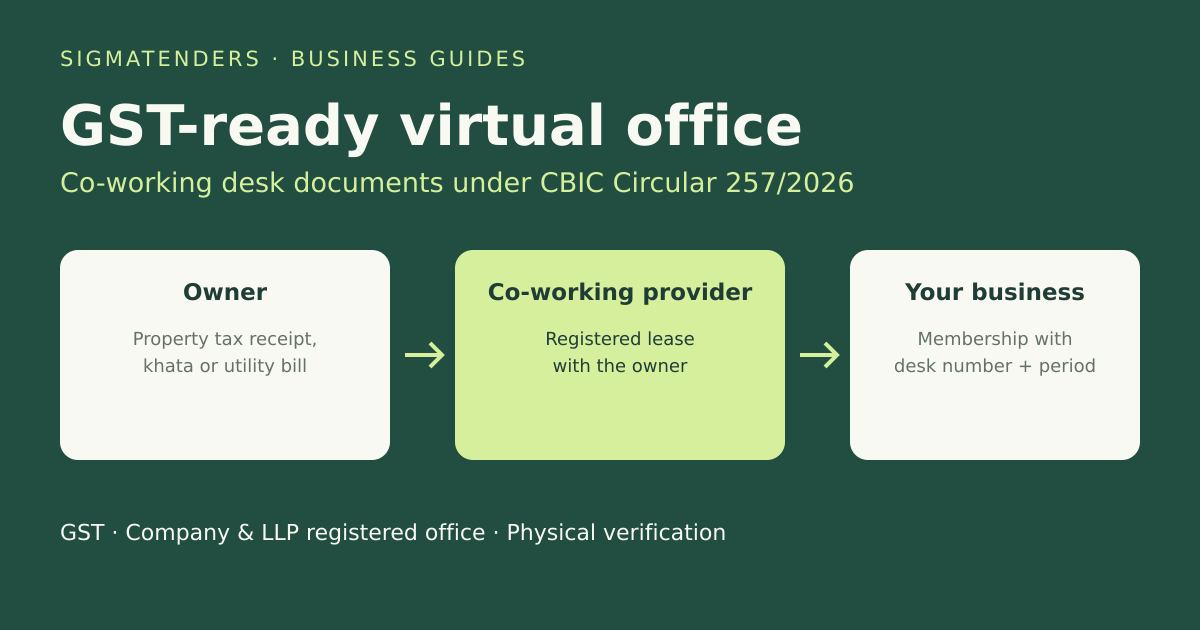
A virtual office gives a remote business an address and agreed services without taking a conventional office. For GST, look beyond the mailing address: CBIC’s co-working route requires a membership agreement with an allotted desk, cabin or suite, its period, and the provider’s ownership proof or registered lease. The documents should explain your connection to an identifiable physical space. Circular 257/03/2026-GST, 26 October 2026, para 3.8.5
SigmaTenders helps Indian founders arrange a GST-ready virtual desk or registered-office address through verified partner co-working spaces. Price on request.
What does a virtual office include?#
“Virtual address” can mean a correspondence service, a registration-document package or a desk membership. Those are different purchases. Decide whether you need somewhere to receive letters, support GST registration, establish a company registered office, or work regularly.
A virtual working space also needs a clear access agreement: ask when you can use the allotted desk and whether meeting rooms cost extra. A plan name alone tells you little about occupancy rights or filing suitability. Our virtual office for GST registration guide covers the application in detail; this page helps you choose the arrangement and city.
Is a virtual office legal for GST registration?#
Co-working premises have an express documentary route under Circular 257. Paragraph 3.8.5 and FAQ Q.26 describe allocated space backed by a membership and property documents. This supports a properly documented co-working arrangement; it is not blanket approval for every product sold as a virtual office. Circular 257, para 3.8.5 and FAQ Q.26
Address-only versus an allotted desk#
An address-only subscription without an allotted desk and supporting lease chain is a weaker basis for the co-working route because it does not demonstrate the structure specified in para 3.8.5. Ask to inspect the membership and property evidence before paying. An address-service invoice alone does not establish those elements. Circular 257, para 3.8.5
| Premises position | Documents to check |
|---|---|
| Every co-working applicant | Membership agreement stating its period, specific allotted suite/cabin/desk number, and whether the provider owns or leases the premises. FAQ Q.26 also specifies the full address and allocated space. |
| Provider owns the premises | Membership plus one qualifying document in the provider’s name: latest property-tax receipt, municipal khata, property-identification document, latest electricity bill or latest water bill. |
| Provider rents or leases the premises | Membership plus the valid registered rent/lease agreement between the property owner and co-working provider. |
These are the alternatives in paras 3.8.2.2 and 3.8.5, Annexure III and FAQ Q.26. Follow the chain owner → provider → applicant. Where an intermediary sells the plan, establish which entity signs your membership and holds the ownership evidence or registered owner–provider lease.
Direct tenancies have a separate route under para 3.8.3, including circumstances where an unregistered agreement is accepted with supporting premises evidence. That does not remove para 3.8.5’s registered head-lease requirement for a provider renting co-working premises. See the rent agreement for GST guide. Circular 257, paras 3.8.3 and 3.8.5
For qualifying consent-based premises, para 3.8.4 prescribes the owner’s plain-paper consent in Annexure VI plus supporting property evidence. Use the GST NOC generator for that route, rather than treating an NOC as a substitute for co-working membership documents. Circular 257, para 3.8.4 and Annexure VI
Can it be a company’s registered office address?#
A virtual company address needs a separate MCA review. Section 12 requires a company registered office capable of receiving and acknowledging communications and notices, and prescribes name-and-address display. Reliable mail handling and premises access therefore matter beyond incorporation day. Companies Act, section 12(1) and (3)
MCA’s INC-22 instruction kit sets out premises evidence, owner/authorised-occupant authorisation and utility evidence not older than two months. A GST document pack does not automatically answer the company filing requirements. MCA INC-22 instruction kit, Rule 25
The Registrar can physically verify a registered office under the applicable process; Rule 25B includes checking address documents and photographing the office. Companies (Incorporation) Third Amendment Rules, 2022, Rule 25B
Read our registered-office address guide and private limited company guide before choosing a plan for incorporation.
Virtual office vs co-working seat vs own office#
Use this practical comparison to decide what to request. Access, storage and support depend on the actual contract.
| Decision | Virtual desk membership | Regular co-working seat | Own or independently leased office |
|---|---|---|---|
| Main purpose | Address, documents and agreed occasional use | Routine work in shared premises | Dedicated operations and control |
| Workspace access | Confirm allotted desk and permitted access | Confirm hours and reserved/shared seating | Set through ownership or tenancy rights |
| Initial commitment | Membership and service scope | Seat subscription and service scope | Purchase/lease, fit-out and operating costs |
| Goods storage | Do not assume it is included | Requires express agreement and suitable space | Assess premises suitability and permissions |
| Registration review | Membership plus provider property evidence | Same co-working document review | Ownership or tenancy evidence |
| Best fit | Remote services with limited premises needs | People needing regular desk access | Teams needing dedicated space or facilities |
The registration row follows the different premises categories in Circular 257, paras 3.8.2–3.8.5. Paying for more space does not replace the documentary checks.
How our partner-desk service works#
The service is available through partner spaces; we confirm availability in your city within 48 hours. Tell us your business activity, intended state, legal form and whether the address is for GST, MCA or both.
We help with four parts:
- Address and document pack: membership with agreement period and allotted desk number, plus the provider’s ownership proof or registered owner–provider lease.
- CA-assisted filing: GST/MCA application support, including checking the proposed address use against the business’s circumstances.
- Verification preparation: reviewing the document pack and arrangements for identifying and accessing the declared premises.
- Mail handling: agreeing how correspondence at the partner space will reach you.
The co-working pack follows Circular 257, para 3.8.5. The GST document checklist helps organise the wider application; our GST registration guide explains the broader process.
Price on request. Before signing, obtain the scope in writing: membership period, desk access, mail arrangements, filing support, renewal and exit terms. Ask which charges sit outside the quotation and who will resolve a document mismatch.
Physical verification: what officers check#
Under Rule 25, physical verification can take place before registration in the specified cases, or after registration. For system-identified applications, Circular 257 para 5.6 directs officers to report whether the declared principal place exists, record efforts to locate a non-existent premises, and upload GPS-enabled site photographs and the report in FORM GST REG-30. Rule 25, Notification 38/2023, clause 6 · Circular 257, para 5.6
Paragraph 5.6 says the report must be uploaded at least five days before the thirty-day period expires. Rule 25(2) specifies at least five working days before the applicable deadline. These are officer reporting requirements, not a promised approval date. Circular 257, para 5.6 · Rule 25(2)
Prepare for a visit
- Check that the building, floor, unit, desk and PIN details consistently identify the actual premises.
- Keep a legible membership and the applicable owner/provider property documents available.
- Agree with the provider how a visiting officer can locate your allotted space and contact you.
- Be ready to explain the real business activity and where work, records and any stock are located.
- Keep contact and mail-handling arrangements current after registration.
These are preparation recommendations based on the address, document and verification provisions in paras 3.7.2, 3.8.5 and 5.6. FAQ Q.35 says applicant/landlord photographs at the premises are not required or accepted as application premises proof; that is distinct from officers’ site photographs during verification. Circular 257, FAQ Q.35 and para 5.6
Paragraph 5.4.1 bars unwarranted documents and presumptive queries, including objections based merely on a signatory living in another state. Paragraph 5.7 addresses deemed approval where no action occurs within Rule 9’s time limits. Ask your CA to assess the actual application record and any notice. Circular 257, paras 5.4.1 and 5.7
Who should avoid a virtual office?#
Choose premises around operations. We recommend a fuller premises assessment for:
- Businesses holding stock: an address service supplies no warehouse. Arrange real storage and declare applicable additional places of business, or APOBs. Warehouses and godowns fall within “place of business”; Circular 257 also covers additional-place details. Official CBIC trade notice, paras 4–5 · Circular 257, para 3.9
- Exporters dependent on refunds: selected exporters of goods can face risk-based verification of credentials and ITC before IGST refunds are released. Assess evidence and cash-flow exposure with a CA. This is not a rule banning co-working addresses. CBIC Instruction 04/2022-GST
- High-ITC trading businesses: we recommend stronger operational and supply-chain review before purchasing a low-use address. Circular 257 identifies fraudulent credit passing without underlying supply as an enforcement concern; it does not prohibit genuine traders from co-working premises. Circular 257, opening paragraphs and para 3.8.5
- Teams needing daily facilities, manufacturing or customer-facing space: choose premises that actually support those activities and obtain advice on relevant permissions.
For business-specific planning, see GST registration for freelancers or GST registration for e-commerce sellers.
Virtual office prices: market benchmarks#
The following advertised examples were checked on 17 November 2026. They are indicative shopping bands, not a market average or SigmaTenders quotation. Annual equivalents are monthly rates multiplied by twelve, not confirmation of annual billing terms.
| Indicative band or segment | Re-verified provider example | Comparison caution |
|---|---|---|
| Specialist entry offer: ₹7,000/year upwards | theGSTco advertises an Amazon VPOB/APOB package from ₹7,000/year | Specialist e-commerce scope; confirm tax treatment and selected state. |
| Entry advertised rates: roughly ₹9,000–13,200/year equivalent | myHQ lists ₹749/month upwards; WeWork lists its business-address plan from ₹1,099/month | myHQ’s headline does not specify one uniform plan; WeWork’s example is an address plan. |
| Branded registration offers: roughly ₹19,200–22,800/year equivalent upwards | WeWork lists GST from ₹1,599/month and business registration from ₹1,899/month | Confirm location, tenure and tax; advertised tenures include 12 and 24 months. |
| Registered address quoted separately | Regus advertises business addresses from ₹17/day; registered business addresses require a call | The entry rate is not a published registration-plan quote. |
Compare the total commitment, taxes, head-lease evidence, desk allocation, access, mail forwarding, signage, filing fees and renewal terms. A low headline price cannot show whether the documents meet your application needs.
Find virtual office services by city#
Use the directory to narrow your search for virtual offices near me, then assess the specific premises and agreement. These are location guides, not confirmed inventory. Availability is through partner spaces and is confirmed within 48 hours. Goa is a state guide.
| City or area guide | State / Union Territory |
|---|---|
| Delhi | Delhi (NCT) |
| Bangalore / Bengaluru | Karnataka |
| Mumbai | Maharashtra |
| Noida | Uttar Pradesh |
| Kochi | Kerala |
| Chennai | Tamil Nadu |
| Gurgaon / Gurugram | Haryana |
| Hyderabad | Telangana |
| Kolkata | West Bengal |
| Pune | Maharashtra |
| Ahmedabad | Gujarat |
| Coimbatore | Tamil Nadu |
| Jaipur | Rajasthan |
| Chandigarh | Chandigarh (UT) |
| Indore | Madhya Pradesh |
| Lucknow | Uttar Pradesh |
| Goa | Goa |
| Bhubaneswar | Odisha |
Choose an address you can explain and maintain, including how mail and visits will be handled. Ask us about a GST-ready address in your city, with your business activity and intended filing purpose. Price on request.
Frequently asked questions#
Is a virtual office the same as a virtual address?
Providers use these terms differently. An address may cover mail alone. For the co-working GST route, check for an allocated desk, membership period and provider property evidence. Circular 257, para 3.8.5
Can several businesses use the same co-working address?
Co-working registration is expressly contemplated. Each applicant needs its own supporting membership and allocated space; a shared building address does not dispense with those documents. Circular 257, para 3.8.5 and FAQ Q.26
Does a GST-ready virtual office also cover my regd address for MCA?
Have the MCA requirements checked separately, including authorisation, premises evidence and current utility proof. The registered-office NOC generator helps draft an authorisation for review; it does not establish occupancy rights. MCA INC-22 instruction kit
How do I compare virtual office providers near me?
Start with the city directory, then request a sample agreement, the property-document chain, access terms and a complete quotation. Confirm who handles mail, renewals and verification enquiries. SigmaTenders confirms partner-space availability within 48 hours; price on request.
Does a virtual office membership guarantee GST approval?
No. The co-working documents address premises evidence; registration remains subject to the applicable application and verification process. Resolve mismatches before filing and review any notice with your CA. Circular 257, paras 3.8.5 and 5.4–5.7