An InstaSpaces virtual office comparison should read the published refund conditions before relying on a broad money-back claim. The checked policy ties its documentation-related full-refund scenario to three or more rejections for the stated provider-document/premises reasons and lists exclusions. That is different from an unconditional refund after the first adverse decision. InstaSpaces refund policy
SigmaTenders is not affiliated with InstaSpaces. This guide independently compares published terms and the evidence to request for an actual desk.
InstaSpaces virtual office: price signals need a selected quote#
The official product-page title advertises a ₹799 starting figure, but the accessible page did not establish a complete plan, term and city-specific charge. An official Mumbai page was also available. Confirm the chosen location and current written total directly. Product page · Mumbai page
Do not turn a starting amount into a national GST-ready price or assume it includes every name-board, professional or mail charge. The actual contract should identify the centre, applicant and intended registration use.
| Criterion | Provider publication checked | What to confirm |
|---|---|---|
| Starting-price signal | ₹799 in the official product title; limited rendered detail. Product | Actual location, tenure, taxes and inclusions. |
| Documentation refund | Specified three-rejection condition. Policy | Causation, evidence, claim procedure and applicable version. |
| KYC outcomes | Policy lists administrative deductions in stated scenarios. Policy | Amounts and conditions relevant to your purchase. |
| Verification | Policy includes applicant/verification-related exclusions. Policy | Who assists and what the service actually covers. |
| GST documents | Review the selected pack. | Allocated-space membership and provider property chain. |
| Renewal/mail | Review the contract. | Continuity, notice, forwarding and exit obligations. |
These are contractual review questions, not a conclusion about any individual application or centre.
Read the refund condition as a condition#
The published policy distinguishes document-related registration rejection from applicant KYC and other issues. It also lists biometric/physical-verification and government-delay factors among exclusions or limitations. Confirm how the terms apply to your facts before purchase. Refund policy
Ask which documents demonstrate that a rejection was caused by the supplied premises pack and who decides the claim. If the policy requires several attempts, understand the resulting time and work before treating it as business continuity protection.
Keep the applicable policy and written quote with the booking. A later website revision should not be your only record of what you reviewed.
A refund clause is a private contractual remedy. It does not bind the tax department, extend a statutory reply deadline or guarantee that the next application will succeed. Have the professional deal with the actual notice/order independently of the provider discussion.
The separate legal test: an allotted co-working space#
Circular 257 does not mention “virtual office”. Paragraph 3.8.5 concerns co-working premises with an allocated suite/cabin/desk, an agreement period and provider ownership/lease status. A mailing-only arrangement without those particulars and supporting rights is weaker. Circular 257
Before paying, ask to see the actual membership and identify which legal entity grants the allocation. Do not assume a generic NOC or an address-service invoice establishes that right.
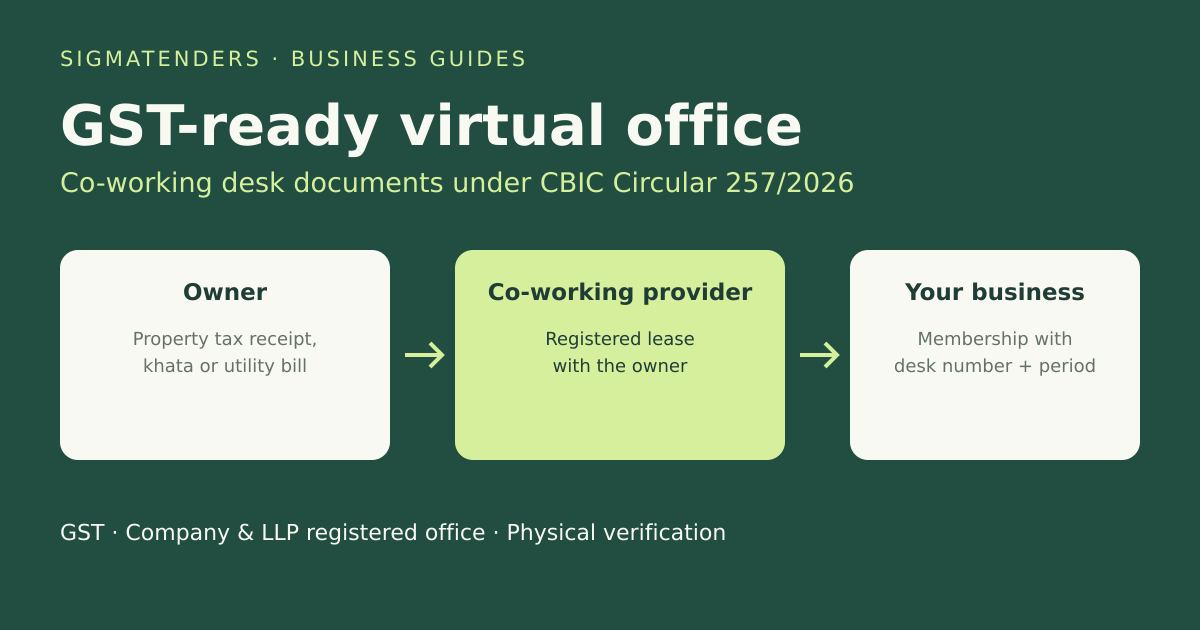
For a provider-owned property, membership is supported by one qualifying provider-name property document. The alternatives include latest property-tax receipt, municipal khata, property-identification document or latest electricity/water bill. Paras 3.8.2.2 and 3.8.5
For a rented property, paragraph 3.8.5 requires the valid registered owner–provider rent/lease agreement plus membership. The applicant’s short term should not be used to remove the supporting registered head lease. Circular 257; FAQ Q.26
Use the GST-ready desk guide to check the chain and the GST document checklist for applicant/signatory evidence.
Avoid creating a problem merely to claim a remedy#
The sensible first step is to inspect documents before filing, not to accept an incomplete pack because a refund may eventually be available. Identify missing names, dates, allocation and lease pages early.
If a clarification arrives, separate genuine omissions from disputed demands. The circular permits clarification of illegibility, address mismatch and vague premises details while limiting irrelevant presumptive queries. Paras 5.4–5.4.1
Reply formally in REG-04 within the applicable period. A provider’s support ticket does not itself constitute that reply. Keep the filed response and acknowledgement alongside any contractual claim. Circular 257, para 5.5
Do not submit repeated applications without fixing the recorded deficiency merely to reach a refund threshold. Ask a CA to review whether correction, reapplication or another remedy is appropriate.
Verification support: define the promised work#
Ask whether support means preparing documents, explaining the membership, coordinating genuine premises access or helping the applicant respond through the portal. Those are different tasks and should be priced explicitly.
The officer’s physical-verification process may include REG-30 and GPS-enabled site photographs. The existence of a refund policy or brand promise does not remove that process. Circular 257, paras 5.1 and 5.6
Provide truthful access to the real allocation. Do not stage employees, stock or equipment to hide a different operation. Where goods are held elsewhere, have the actual premises and registration position assessed.
For a combined company/GST package, ask for a separate MCA document review rather than assuming that the same NOC and bill meet every requirement.
Mail, renewal and plan changes#
Agree how official letters are accepted and logged, when the founder is alerted and which forwarding or scanning charges apply. Check who remains responsible when the applicant is travelling.
For renewal, confirm the allocation and provider property chain remain valid. If the operator moves or loses its own lease, ask who supplies replacement documents and assists with the transition.
Read charges for name changes and document corrections in the applicable contract. Discuss potential incorporation-name changes before buying, rather than assuming every revision is free.
Compare the total term cost and service responsibilities. A lower entry figure may reflect a different scope from a plan that includes professional application support.
The SigmaTenders service to compare#
SigmaTenders uses an allotted-desk co-working membership through verified partner spaces. We help with membership/property documents, CA-supported GST/MCA applications, physical-verification preparation and mail handling.
Price on request. It is available through partner spaces; we confirm availability in your city within 48 hours. This comparison makes no promise of a better approval rate, cheaper offer or particular refund entitlement.
Read the virtual office overview, then ask us about your desk and application-support requirements. This is general information, not legal or tax advice. Availability confirmation is separate from government processing.
InstaSpaces virtual office FAQs#
Does the checked policy promise a refund after one rejection?
Its documentation-related full-refund scenario specifies three or more rejections for the stated reasons. Read all applicable conditions and exclusions. Published policy
Is the ₹799 starting signal an all-inclusive national GST plan?
The accessible product page did not establish that. Obtain a current written quote for the selected location, plan and term. Official page
Should I rely on a refund instead of checking the provider's lease?
Inspect the pack first. For a rented co-working centre, paragraph 3.8.5 specifies the membership and registered owner–provider agreement. Circular 257
Does provider support replace my REG-04 reply?
No. Ensure the formal reply is filed within the applicable period, independently of private support or refund discussions. Circular 257, para 5.5