A myHQ virtual office purchase involves choosing a plan and an actual workspace operator. The useful comparison is therefore the selected centre, its document chain and who must resolve a problem, alongside the marketplace’s published offer. myHQ product page
SigmaTenders is not affiliated with myHQ. This independent guide uses dated provider information and practical contract-review questions; it does not rate every location or assume identical terms across a network.
myHQ virtual office: what is published and what needs a quote?#
The product page distinguishes business-address, GST-registration and company-registration plans. Its city tiles include Bangalore, Delhi and Mumbai and advertise ₹749/month starting prices. The official pricing help article instead states ₹799/month as a starting figure. Both were checked on 17 November 2026. Product page · Pricing help
Those figures should not be combined into a verified all-inclusive tariff. Ask which selected plan, location, tenure, taxes and date the seller’s actual quote covers. A discrepancy between general pages is a reason to obtain a written offer, not evidence of an applicant’s final contractual price.
The terms identify the platform operator and include conditions relating to KYC and third-party arrangements. Read the terms that apply to the actual purchase rather than assuming the headline page supplies the whole contract. Provider terms
Marketplace versus location: define responsibility#
Before payment, identify the entity taking the booking, the operator granting space and the person supplying documents. These roles may be different. Ask who must obtain the property evidence and correct an error.
| Criterion | Published myHQ information | What the buyer should establish |
|---|---|---|
| Plan selection | Separate address, GST and company categories. Product page | Exact intended filing and selected centre. |
| Headline price | Product/help pages show differing starts. Product · Help | Written total for the actual term and scope. |
| Supporting documents | Product page describes NOC, utility and agreement material. Product page | The specific membership and property chain for the centre. |
| Platform terms | Operator and purchase conditions are published. Terms | Who is contractually responsible for each deliverable. |
| Refund | Product page promotes a money-back arrangement. Product page | Applicable triggers, deadlines, deductions and recipient of claim. |
| Continuing service | Verify against the selected agreement. | Renewal, mail, name display, visits and exit assistance. |
The table distinguishes publication from what remains to be established. It does not conclude that documents are missing or that any individual centre fails legal requirements.
Apply Circular 257 to the chosen premises#
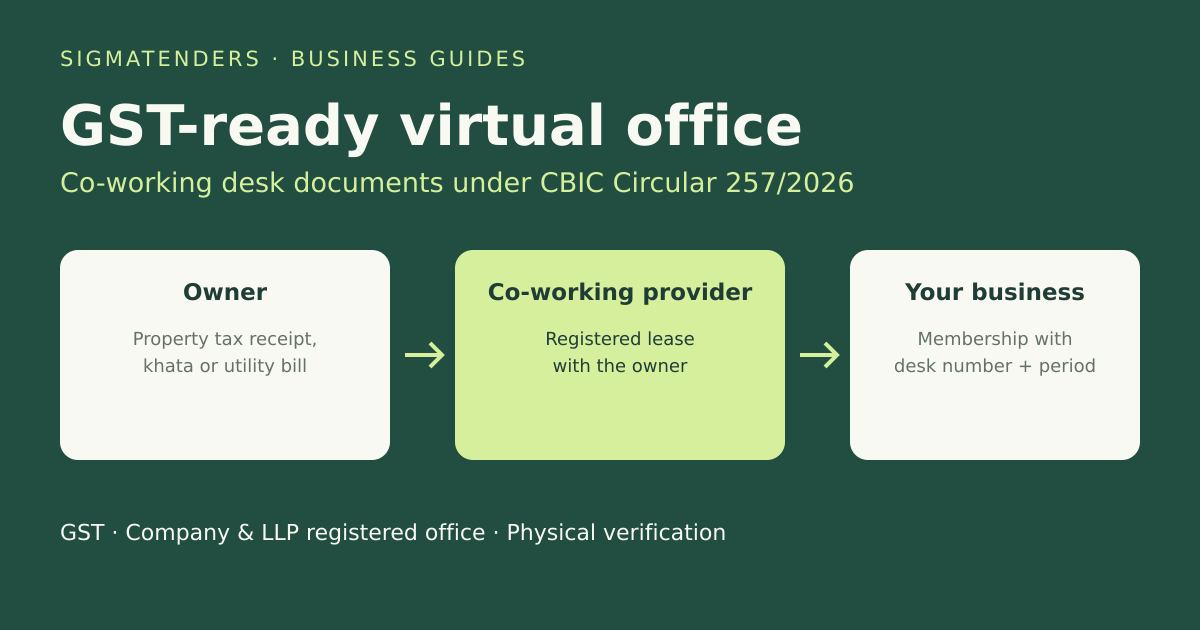
Circular 257 does not mention “virtual office”. Paragraph 3.8.5 instead describes a co-working membership with the allotted suite/cabin/desk number, agreement period and provider ownership or lease status. A postal-only service without those facts and the right chain is weaker. Circular 257
For a provider-owned property, prepare membership plus one qualifying provider-name property document. The alternatives include latest property-tax receipt, municipal khata, property-identification document or latest electricity/water bill. Paras 3.8.2.2 and 3.8.5
For rented premises, the specified evidence is membership plus the valid registered owner–provider lease/rent agreement. A generic NOC-and-bill description does not itself answer whether that registered agreement is available. Ask to inspect it for the selected operator. Para 3.8.5 and FAQ Q.26
Check names, complete address and actual allocated unit. An aggregator’s invoice may establish payment while leaving the provider’s occupation rights to be proved through other documents.
Read the GST virtual-desk guide for the full category and the GST documents checklist for applicant and signatory evidence.
Be precise about state expansion and APOB#
A marketplace may offer locations in several states, but each registration needs its own factual review. Paragraph 3.9 concerns additional places within the relevant registration state; another state’s warehouse should not simply be treated as a local APOB under an existing GSTIN. Circular 257, para 3.9
Before buying a multi-location package, map where goods are held, where supplies are made from and what each proposed desk will actually support. Have the CA assess liability and the premises documents for each state.
A location package should not encourage declaring stock at a desk that cannot hold it. Describe the real operating model and request the correct document arrangement rather than selecting a plan solely because “e-commerce” appears in its name.
Refund language needs the full conditions#
Ask for the policy version and contract applicable to your booking. Identify whether the claim concerns document errors, applicant KYC, cancellation, a change of mind or a departmental rejection.
Record the trigger date, required evidence, notice method and any non-refundable components. Read the selected operator’s responsibilities alongside the platform terms.
A refund is a contractual remedy. It does not guarantee that an officer will accept a document, extend a deadline or approve the application. Avoid planning the business around an unconditional approval outcome merely because a headline sounds reassuring.
For a clarification, the circular still requires a timely formal response. Provider discussions should not distract the applicant from monitoring and answering REG-03 through the prescribed route. Circular 257, paras 5.4–5.5
Mail, verification and renewal after the purchase#
Ask how letters are logged, what notification is sent and who handles urgent official correspondence. Clarify forwarding charges and collection arrangements.
For a premises visit, establish genuine access to the declared allocation and the person who can explain the arrangement. The GST officer’s process can include REG-30 and GPS-enabled photographs; no marketplace label removes that route. Circular 257, paras 5.1 and 5.6
For renewal, ask whether the same desk allocation and property chain remain valid. If the provider moves or loses its lease, identify who supplies replacement documents and how address changes and mail continuity are managed.
These practical questions apply equally when comparing a small operator, marketplace listing or nationally known workspace.
Compare the SigmaTenders support scope#
SigmaTenders structures its address service as a co-working membership with an allotted desk number through verified partner spaces. We help with membership/property evidence, GST/MCA applications with a CA, physical-verification preparation and mail handling.
Price on request. It is available through partner spaces; we confirm availability in your city within 48 hours. This does not promise a particular building, cheaper price or registration approval.
Use the virtual office overview to define the service you need. Ask us about your proposed address and application scope with the entity, city and actual activity. This is general information, not legal or tax advice.
myHQ virtual office FAQs#
Which myHQ starting price should I rely on?
Does a marketplace booking identify the legal space provider?
Check the executed membership and purchase terms. Identify who grants the allocated space and which property evidence supports that person’s rights.
Can I treat another state's warehouse as an APOB under my present GSTIN?
Additional places under paragraph 3.9 are within the registration state. Have the separate-state position assessed before purchasing locations. Circular 257
Does a money-back offer guarantee GST approval?
No. Read the applicable contractual conditions and separately satisfy the legal requirements. A provider’s refund arrangement does not bind the department.