A virtual office for GST registration in Bangalore should be reviewed using Karnataka’s own implementation guidance. Circular GST-01/2026 applies CBIC Circular 257 to KGST, with the central text attached. Use that document to assess the membership and property chain before booking, rather than relying on anecdotes about shared addresses. Karnataka circular
The important distinction is between a real allocated co-working space and an address-only service. The filing should describe the arrangement you actually have.
Virtual office for GST registration in Bangalore: the evidence test#
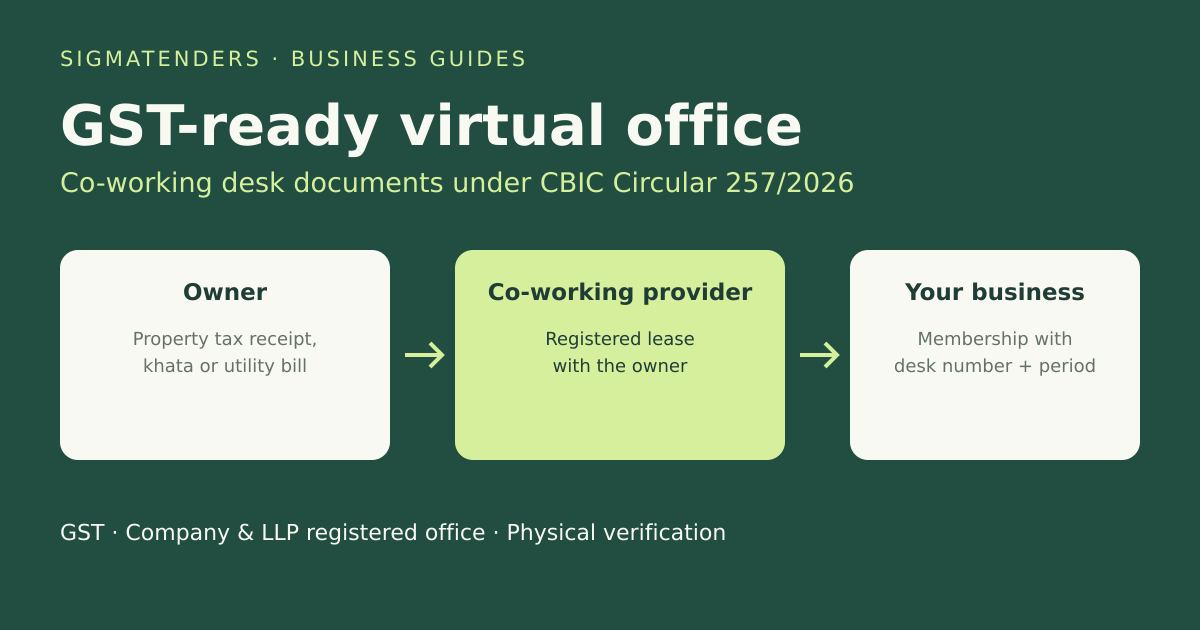
The attached Circular 257 does not use “virtual office”. Paragraph 3.8.5 concerns a co-working membership identifying an allocated physical space. A mailing-only plan without that allotment and the correct supporting documents is weaker. Para 3.8.5
| Before booking | What should be available |
|---|---|
| Applicant allocation | Specific suite/cabin/desk number and the membership period. |
| Property status | Membership states whether the provider owns or leases the premises. |
| Provider owns | One qualifying property document in the provider’s name. |
| Provider rents | Valid registered owner–provider rent/lease agreement. |
| Address | Full premises details consistent across the chain. |
These follow paras 3.8.2.2, 3.8.5 and FAQ Q.26. Ownership-document alternatives include latest property-tax receipt, municipal khata, property-identification document or latest electricity/water bill.
A khata/property identifier and a desk number are not interchangeable. The property record concerns the underlying premises, while the membership identifies your allocation within it. The co-working category does not require every applicant to manufacture a separate municipal record for a desk.
For the complete entity and signatory pack, use the GST document checklist.
1. Check the real operator and the term#
Ask which legal person grants the membership and whether its name connects to the ownership or registered lease evidence. If a booking platform differs from the provider, have the final documents explain the actual occupation chain.
Read the membership period and access terms before payment. Confirm that the allotted unit exists and can be identified. A provider should not need to invent a new allocation after an official query arrives.
Ask who supplies corrected or refreshed documents during a resubmission. Treat document continuity and mail handling as contractual scope, not assumptions inferred from a logo.
The Bangalore city guide covers wider location and service comparisons. This page concentrates on the filing sequence.
2. Confirm Karnataka stamping and the registered head lease#
Karnataka’s Stamp Act includes digital e-stamping, with the state Digital E-Stamp Rules providing its framework. Payment of duty is separate from any required deed registration. State Act · Digital rules
For the covered leases, section 17(1)(d) of the central Registration Act includes year-to-year terms, periods exceeding one year and yearly-rent arrangements. Have the actual contract and state provisions assessed rather than relying only on an eleven-month description. Registration Act
The co-working GST route is explicit for a rented centre: supply the registered owner–provider lease plus applicant membership. The direct-tenant alternatives in paragraph 3.8.3 should not be used to delete that paragraph 3.8.5 supporting document. Karnataka-hosted Circular 257
Request the instrument’s classification and current duty/fee calculation from the drafter. This page does not establish a fixed Karnataka stamp amount for every agreement.
3. Prepare the Bengaluru premises record#
Write out building, floor, unit/allocation, road/locality and PIN against the executed documents. Bengaluru and Bangalore may both appear in correspondence, but the premises should remain unambiguous and consistent rather than containing conflicting numbers.
Paragraph 3.7.2 requires a specific address matching the supporting evidence. A campus or road name alone may not identify the unit. Confirm the map marker at the actual premises, not the marketplace’s sales office. Circular 257
If stock or another operating location exists, tell the CA. Additional places within Karnataka need their own review under paragraph 3.9; another state’s warehouse cannot simply be added as a Karnataka additional place. Circular 257, para 3.9
4. Complete Part A and the applicant sections#
Use the official GST normal-taxpayer registration service. Complete Part A, validate the required contact details and retain the TRN. Continue Part B with the entity, promoter/partner and authorised-signatory particulars. GST registration manual
Ensure the applicant legal name/PAN and authority documents match the chosen constitution. A founder’s personal PAN and a company’s PAN are not substitutes merely because the same person controls both.
Keep account and contact access with the business. Agree who monitors notices so that a clarification does not sit unread in an adviser’s inbox.
5. Select possession and review state/central jurisdiction#
Select the nature of possession matching the membership and the live form’s available labels. Use a dedicated co-working option where applicable; otherwise have the CA match the real arrangement to the correct available category, retaining the full prescribed evidence. Circular 257, paras 3.8.2–3.8.5
The current manual describes map-based state-jurisdiction suggestions and reset/manual review where necessary. Check the actual Bengaluru address/PIN and central jurisdiction separately. GST manual
Use the Karnataka GST department portal for current departmental circulars and contact/jurisdiction resources. The department also publishes a helpdesk directory and state/central jurisdiction mapping. Do not copy an old office assignment solely from a blog or confuse ROC Bangalore with GST jurisdiction.
If the live mapping appears wrong, preserve the correct address evidence and seek official assistance. Do not change the true premises to suit a convenient dropdown.
6. Upload, submit and complete authentication#
Check each field’s current type and size limit. Combine complete pages where the form permits, compress legibly and reopen the uploaded file. The registration manual distinguishes premises, photograph and e-KYC field limits. GST manual
Before submitting, compare the saved allocation and applicant name against the membership. Make sure the registered head lease’s relevant parties, premises and validity remain readable.
Complete the authentication step communicated by the portal. Applicants selected for biometric, photograph and original-document verification at a facilitation centre need to complete that route; paragraph 5.2 links completeness to successful verification. Circular 257
Retain the ARN when generated and use it for tracking. A TRN, authentication email or ARN should not be advertised to customers as an approved GSTIN. GST manual
Physical verification at the actual desk#
The ordinary successful Aadhaar route and thirty-day physical-verification cases have different processing provisions. A successful authentication does not universally prevent selection for a premises visit. Circular 257, para 5.1
The officer’s REG-30 includes GPS-enabled site photos and relevant documents, with the report uploaded at least five days before the thirty-day period expires. Prepare honest access, accurate directions and an explanation of the genuine business arrangement. Para 5.6
FAQ Q.35 rejects applicant/landlord photographs as application premises proof; that is different from official site photographs or the facilitation-centre identity process. Do not collect selfies as a replacement for the missing lease chain. FAQ Q.35; paras 5.2 and 5.6
Clarifications and the service scope#
For REG-03, answer the actual grounds in REG-04 within seven working days of receipt. The circular restricts presumptive queries while allowing genuine document/address clarification. Its deemed-approval provision applies against the correct Rule 9 period and processing stage. Paras 5.4–5.7
Use the GST rejection guide if an order is issued, and the national virtual-desk GST guide for the full evidence framework.
SigmaTenders assists with membership/property documents, CA-supported GST/MCA applications, verification preparation and mail handling. Price on request. It is available through partner spaces; we confirm availability in your city within 48 hours. Ask us about a Bangalore desk for GST registration. Availability confirmation is separate from departmental processing.
Bangalore GST address FAQs#
Does Karnataka formally apply the co-working guidance?
Its GST-01/2026 circular applies CBIC Circular 257 to KGST implementation, with the central text attached. Official Karnataka circular
Must every Bengaluru desk have its own municipal khata?
The circular lists qualifying provider ownership documents as alternatives and separately requires the membership allocation. Do not confuse a property identifier with a desk number. Paras 3.8.2.2 and 3.8.5
Can a digital e-stamp replace the provider's registered lease?
No. Stamping and registration are separate questions, and the rented co-working route specifies the registered owner–provider agreement. State rules · Para 3.8.5
Does Aadhaar authentication guarantee no premises visit?
No. Risk-based or authorised physical verification can still apply under the circular’s process. Paras 5.1 and 5.6