A virtual office for GST registration in Delhi should be chosen against the exact premises and the document route you will file. Start with the allotted desk and the provider’s property rights, then confirm the Delhi state ward and central jurisdiction. A familiar locality name does not select those fields for you. Circular 257, paras 3.7.2–3.8.5
This guide follows the work from reviewing a proposed membership to tracking the ARN. For a wider location comparison, see the Delhi virtual-office guide.
Virtual office for GST registration in Delhi: assess the desk first#
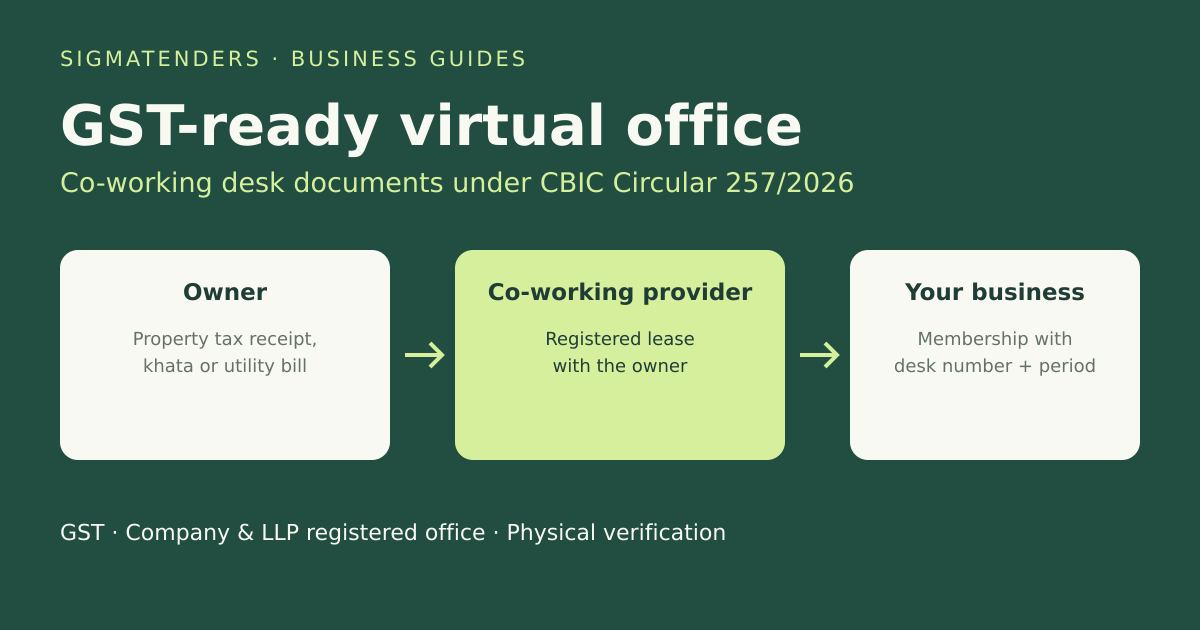
The circular does not mention “virtual office”. Paragraph 3.8.5 specifies co-working premises where the applicant has an identified allocated space and supplies membership plus provider property evidence. A postal-only plan without those elements is weaker. Circular 257
Before paying, request a sample membership and ask which legal entity provides the desk. Confirm whether that entity owns the property or leases it from the owner.
| Review item | Evidence to obtain |
|---|---|
| Allocated space | Specific suite/cabin/desk number and full premises address. |
| Membership period | Clear start/end or term provisions matching the arrangement. |
| Provider status | Ownership or lease status stated in the membership. |
| Provider owns | One qualifying provider-name property document plus membership. |
| Provider leases | Valid registered owner–provider lease/rent agreement plus membership. |
Qualifying ownership evidence includes latest property-tax receipt, municipal khata, property-identification document or latest electricity/water bill. FAQ Q.26 reinforces the complete address and allocated area. Paras 3.8.2.2 and 3.8.5; FAQ Q.26
A second NOC or a provider’s electricity bill does not replace the registered owner–provider lease in the rented-centre route. Have that gap resolved before booking for GST use.
1. Confirm Delhi NCT and the principal-place facts#
Do not use “Delhi NCR” as the registration state. Establish whether the actual property is in Delhi, Uttar Pradesh or Haryana and enter the correct state in the application. Additional places under paragraph 3.9 are within the relevant registration state. Circular 257, paras 3.7 and 3.9
Prepare the final address against the documents: building, floor/unit, allotted space, road/locality and PIN. Check that the location is appropriate to the business’s real arrangements and identify any stock location separately.
A desk is not a substitute for a warehouse or production facility you actually use elsewhere. Ask the CA how operational locations should be declared rather than reducing every business address to one correspondence point.
2. Review Delhi agreement registration and stamping#
Delhi Revenue identifies e-stamping as the duty-payment route. Its page lists lease registration fees of ₹1,000 per instrument plus ₹100 pasting fee, checked on 17 November 2026. That fee is separate from stamp duty and is not a quote for your whole membership. Delhi Revenue
For the covered leases, section 17(1)(d) of the Registration Act includes year-to-year terms, periods exceeding one year and yearly-rent arrangements. Have the actual instrument reviewed rather than relying on an eleven-month shortcut. Registration Act
For GST co-working evidence where the provider rents, paragraph 3.8.5 expressly specifies the registered owner–provider agreement regardless of how short your own membership may be. Stamping or notarisation should not be presented as equivalent to that registration. Circular 257
Ask the drafter to confirm classification and current duty before execution. Do not borrow Delhi property-sale percentages to calculate a workspace agreement.
3. Prepare applicant and signatory documents#
Complete the constitution-wise pack before opening REG-01. The applicant’s PAN, legal name, constitution proof and relevant people/authorisation documents must match the chosen entity. Annexure II supplies the entity-wise framework. Circular 257, Annexure II
Use the GST document checklist rather than asking the provider to supply documents it cannot verify, such as your partnership authority or company director details.
Check who controls the registered email and mobile number. An adviser may assist, but the founder should be able to monitor official notices and recover the application record.
4. Complete Part A, then the premises section in Part B#
Use the official GST portal’s normal-taxpayer registration service, complete Part A and retain the TRN. Enter the business and people details in Part B before reviewing the principal place. The TRN is a draft reference, not approval. GST manual
Select the nature of possession that corresponds to the signed arrangement. Where the live form has a co-working-specific option, use the applicable category; otherwise have the CA match the available label to the actual rights and retain the paragraph 3.8.5 evidence. Circular 257, paras 3.8.2–3.8.5
Do not select “Own” because the provider or director owns the premises. The applicant’s legal relationship determines its category.
5. Check the map, Delhi ward and central jurisdiction#
The GST manual now describes a Get State Jurisdiction function based on entered premises coordinates, with reset/manual selection where necessary. Review the suggested result instead of assuming map automation makes an inaccurate address correct. Current GST manual
Delhi’s ward-wise area publication and Trade and Taxes portal provide state-department resources. Confirm the live mapping for the real premises and PIN, and separately check the central jurisdiction. Do not apply an old ward table without reconciling changes.
If the map pin or jurisdiction appears wrong, preserve the address evidence and seek official technical assistance as needed. Altering the actual location to fit the dropdown is not a solution.
6. Upload, review and complete authentication#
Use readable complete documents and obey each field’s live size/type instruction. The manual identifies PDF/JPEG uploads with field-specific limits; compression should preserve parties, address, signatures and registration details. GST manual
Recheck the saved application before submission. In particular, compare the legal applicant and allocated unit with the membership, and open the lease pages that establish the provider’s rights.
Complete the authentication route communicated by the portal. Where biometric/photo/original-document verification at a facilitation centre applies, the circular links completeness to successful completion of that step. Do not promise an ARN before the necessary checks finish. Circular 257, para 5.2
After the system generates an ARN, retain it for tracking. An ARN is an application reference; it does not mean the GSTIN has been granted. GST manual
Physical verification and notice handling#
Aadhaar authentication does not universally remove premises verification. The circular provides a thirty-day route for specified cases and requires the officer’s REG-30 with GPS-enabled site photographs at least five days before that period expires. Paras 5.1 and 5.6
Prepare accurate directions and honest access to the actual allocation. Ask the provider how an official visit is handled and how the founder is contacted. Do not stage stock, staff or equipment inconsistent with the business.
For REG-03, reply in REG-04 within seven working days of receipt. Paragraph 5.4.1 limits irrelevant presumptive queries, but genuine document omissions and mismatches still need correction. Paragraph 5.7 provides deemed approval if no action is taken in the applicable period; calculate the correct stage and dates. Paras 5.4–5.7
If a rejection order is issued, use the GST registration rejected guide for the distinction between correction/reapplication and professional review of remedies.
Arrange the Delhi support scope#
SigmaTenders helps with membership/property documents, GST/MCA applications with a CA, verification preparation and mail handling through verified partner co-working spaces. Price on request. It is available through partner spaces; we confirm availability in your city within 48 hours.
Compare the national GST-ready desk guide before selecting a plan. Ask us about a virtual desk for GST registration in Delhi with your business activity, entity and any stock/refund-related needs. The availability response is separate from departmental processing.
Delhi GST desk FAQs#
Can a Noida address be filed as Delhi because it is in NCR?
Use the actual state of the premises. A broad NCR label does not merge Delhi and UP registrations or additional-place treatment. Circular 257, paras 3.7 and 3.9
Does Delhi e-stamping complete the provider's lease registration?
Treat duty payment and registration separately. For a rented co-working centre, paragraph 3.8.5 specifies a valid registered owner–provider agreement. Delhi Revenue · Circular 257
How do I select the Delhi state ward?
Check the live portal’s premises-based suggestion, exact address and official state resources. Central jurisdiction is a separate check. GST manual · Delhi ward publication
Can the provider guarantee a GSTIN after I receive an ARN?
No. The ARN tracks the application; processing, authentication, clarification and verification depend on the applicable route. GST manual · Circular 257, paras 5.1–5.7