A virtual office for GST registration in Mumbai should be reviewed for Maharashtra’s agreement requirements and the electricity particulars needed in REG-01. Obtain those details with the allotted-desk documents before filing, then check the state and central jurisdiction against the real premises. Circular 257, paras 3.7–3.10
This is a filing guide from provider review to ARN tracking. The Mumbai city overview covers broader area, company-use and price comparisons.
Virtual office for GST registration in Mumbai: review the real allocation#
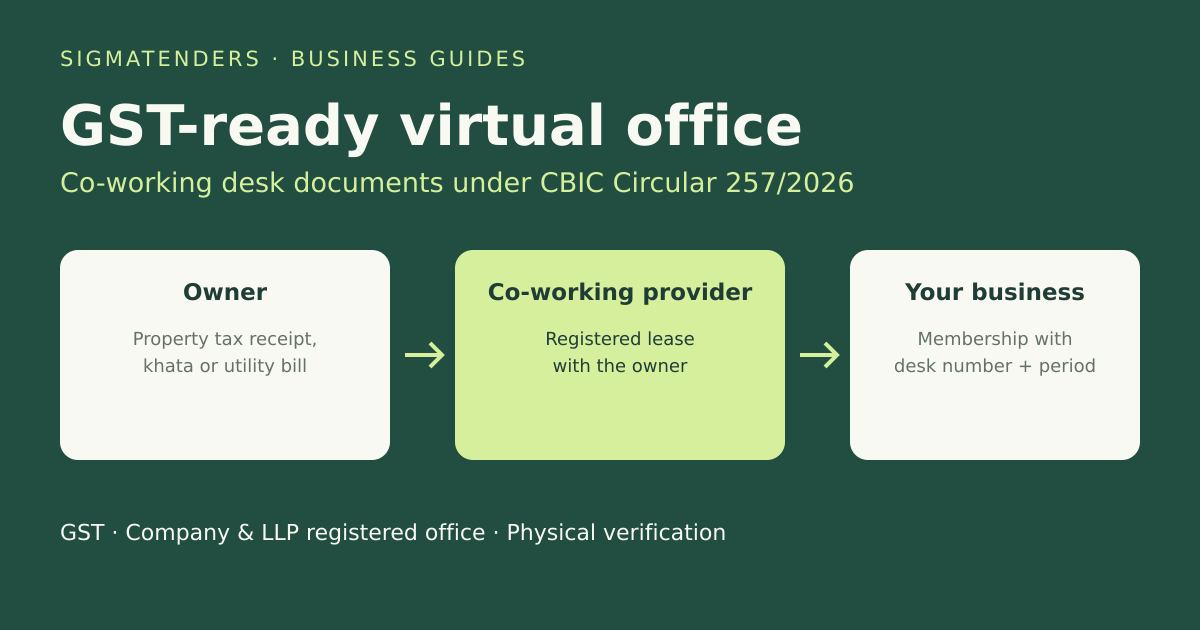
Circular 257 does not mention “virtual office”. Paragraph 3.8.5 addresses co-working premises with an identifiable allocated space and a membership backed by provider property evidence. A postal-only plan without the desk and right chain is weaker. Circular 257
| Before committing | Document or fact to verify |
|---|---|
| Applicant’s space | Specific allotted suite/cabin/desk number, not just a reception address. |
| Membership particulars | Agreement period and whether the operator owns or rents/leases. |
| Provider owns | One qualifying provider-name property document plus membership. |
| Provider rents | Valid registered owner–provider rent/lease agreement plus membership. |
| Premises description | Full address matches the evidence and can identify the location. |
The ownership alternatives include latest property-tax receipt, municipal khata, property-identification document or latest electricity/water bill. FAQ Q.26 reinforces complete address and allocated-space details. Paras 3.8.2.2 and 3.8.5; FAQ Q.26
Ask who supplies the pack if the booking platform is an intermediary. The legal entity granting membership should have a demonstrable connection to the property evidence.
1. Check the Maharashtra agreement position#
Section 55 of the Maharashtra Rent Control Act requires the covered letting/leave-and-licence agreements to be written and registered. A short term should not be advertised as a universal exemption. Have the drafter assess the statute’s scope and the actual instrument. Official Act
The state Stamp Act has different instrument entries. Ask for a current assessment rather than treating a licence rate as automatically applicable to every workspace membership. Maharashtra Stamp Act
Separately, GST paragraph 3.8.5 calls for a registered owner–provider lease where the operator rents. Your own membership and the provider’s supporting lease perform different roles; a short membership does not excuse the missing registered head lease. Circular 257
Request complete readable pages showing the relevant parties, premises, validity and registration. A payment receipt for documentation is not the registered instrument itself.
2. Build the premises and electricity record#
Maharashtra is expressly named in paragraph 3.10 for electricity-board/unit and consumer-account particulars. Ask for those exact identifiers while collecting the agreement and property documents. Circular 257, para 3.10
Record the building, wing/tower, floor, allocated unit, locality and PIN. Where a bill covers a larger building, make the relation to the allocated space clear through the actual membership and property chain.
Do not fabricate an individual desk meter or select a possession category solely to avoid a field. Have the CA explain genuine shared-connection evidence and correct any inconsistent address descriptions.
Also establish whether goods are stored elsewhere. Additional places in the registration state need their own assessment and supporting evidence; another state’s warehouse is not simply a Maharashtra additional place. Circular 257, para 3.9
3. Prepare the applicant before starting REG-01#
Collect the PAN/legal-name details, constitution document, relevant promoter/partner/director particulars and signatory authority. Annexure II differentiates the requirements by business constitution. Circular 257, Annexure II
Use the GST document checklist to prepare this group. A desk provider can supply premises documents but cannot establish your internal signatory authority from a sales enquiry alone.
Agree who controls the email/mobile and monitors official messages. The applicant should retain its own records and access even where an adviser handles preparation.
4. Complete Part A and continue using the TRN#
Open the official normal-taxpayer registration service, enter the state and applicant details, complete the required contact verification and retain the TRN. Continue into Part B with business, people, premises and activity particulars. GST manual
Use the reason for registration and business details that reflect the actual facts. The application should not describe storage or production at a desk merely to resemble a trading or manufacturing operation.
The TRN permits continuation of a draft; it is not a GSTIN or evidence of approval. Keep the final submitted version as well as the draft reference. GST manual
5. Check possession, map and both jurisdictions#
Select the nature of possession corresponding to the contract. If a dedicated co-working option is available, use the applicable label; otherwise have the CA reconcile the available form options with the actual membership and paragraph 3.8.5 evidence. Circular 257, paras 3.8.2–3.8.5
Use the map to locate the real building and review any state-jurisdiction suggestion. The current manual describes map-based suggestion and reset/manual review where appropriate. Central jurisdiction needs a separate check. GST manual
The Maharashtra GST department portal is the official state resource. Do not use Mumbai-I/Mumbai-II ROC labels as GST jurisdiction: corporate registrars and tax officers are different systems.
If a broad metropolitan listing actually points to another Maharashtra district, confirm the real address instead of changing it to a more familiar Mumbai locality.
6. Review uploads and authentication before expecting an ARN#
Check every upload field’s live type/size limit and use complete readable scans. Do not remove lease pages that identify the parties or registration merely to reduce file size. Compress carefully and inspect the saved result. GST manual
Compare the final membership name, period and allocation with the application. Check the electricity account separately, since correct premises proof does not make a mistyped consumer field accurate.
Complete the authentication route communicated by the system. Where selected biometric/photo/original-document verification at a facilitation centre applies, the circular links application completeness to successful verification. Circular 257, para 5.2
Retain and track the ARN when issued. It identifies the application; the GSTIN and certificate follow grant. GST manual
Physical verification and formal clarification#
Specified physical-verification cases use the thirty-day route. The officer uploads REG-30 with GPS-enabled site photographs and other relevant evidence at least five days before the period expires. An applicant’s Aadhaar authentication does not universally remove a premises visit. Circular 257, paras 5.1 and 5.6
Prepare honest access to the allotted space, readable documents and accurate directions. Ask the provider how official visits and correspondence are managed.
REG-03 is a clarification, not a rejection. Reply in REG-04 within seven working days of receipt, addressing each ground. The circular limits presumptive queries but permits genuine document/address corrections. Its deemed-approval provision depends on the applicable Rule 9 period and stage. Paras 5.4–5.7
Use the GST rejection guide when an actual order is issued.
Mumbai grievance resources and choosing support#
Mumbai Central GST published a dedicated registration-grievance mechanism for applicants under central jurisdiction. Use the current official route and identify whether the application is centrally or state assigned before escalating. The published central channel should not be assumed to cover every state-administered case. Official announcement
For state matters, use current resources on the Maharashtra department portal. Preserve the ARN, dates, notice and filed reply so that the issue can be explained precisely.
SigmaTenders assists with membership/property documents, GST/MCA applications with a CA, verification preparation and mail handling through verified partner spaces. Price on request. It is available through partner spaces; we confirm availability in your city within 48 hours.
Read the national GST virtual-desk guide, then ask us about a Mumbai desk for GST registration. Availability confirmation is separate from departmental processing.
Mumbai GST desk FAQs#
Does an eleven-month licence avoid Maharashtra registration questions?
Do not assume that. Section 55 requires covered letting/licence agreements to be written and registered; have applicability assessed. Official Act
Why does the CA ask for an electricity consumer number?
Paragraph 3.10 specifically includes Maharashtra’s electricity-board/unit and consumer particulars in the state-specific information. Circular 257
Does Mumbai's central grievance channel cover every GST application?
The announcement specifies central-jurisdiction applicants. Establish which administration handles the application before using an escalation route. Official announcement
Can a GST-ready desk eliminate physical verification?
No such promise follows from the membership. The applicable verification route remains, including REG-30 site evidence where selected. Circular 257, paras 5.1 and 5.6